Tax deductions vs. Tax Credits: What’s the difference?

Man pointing at a question mark

There are numerous ways to decrease the tax burden, with tax deductions and tax credits being the most popular ones. Many people confuse the differences in both phrases and frequently use them interchangeably. However, they’re two very distinct mechanisms. Both indeed decrease what needs to be paid in taxes, but tax deduction lowers the taxable income for the year.


Meanwhile, tax credit offers a dollar-for-dollar reduction of the owed tax, helping increase the refunds in some cases. A solid strategy made after consulting experienced tax planning advisors or tax accountants can help you save some cash. Let’s look at some of the key things that help differentiate tax credits from tax deductibles.


Taxation 101

What’s a Tax Credit?

Simply put, tax credits directly decrease the tax amount owed, offering a dollar-for-dollar reduction. Qualifying for a $4000 tax credit would imply that you’ll save $4000 on the tax bill. If not, you’ll get a tax refund. For instance, if you qualify for a refundable tax credit of $1500 and you owe only $1000 in taxes, you’ll receive a tax refund for the $500 credit in excess on the tax bill.


However, not all tax credits are refundable. If the tax credit is non-refundable, it might reduce the tax bill down to $0, but even if the credit was worth more than what you owe, non-refundable credits don’t result in checks from the IRS for the difference. Common refundable tax credits include child tax credits and earned income tax credits. Child and dependent care credit and saver’s credit are some examples of non-refundable credits.


American opportunity tax credit is another tax credit that’s often listed as a partially refundable tax. It’s designed to help families pay for higher education expenses worth up to a limit. If you are or have a dependent who qualifies eligible student, and the tax credit is more than the owed taxes, a significant percentage of the leftover amount could be issued as a refund.
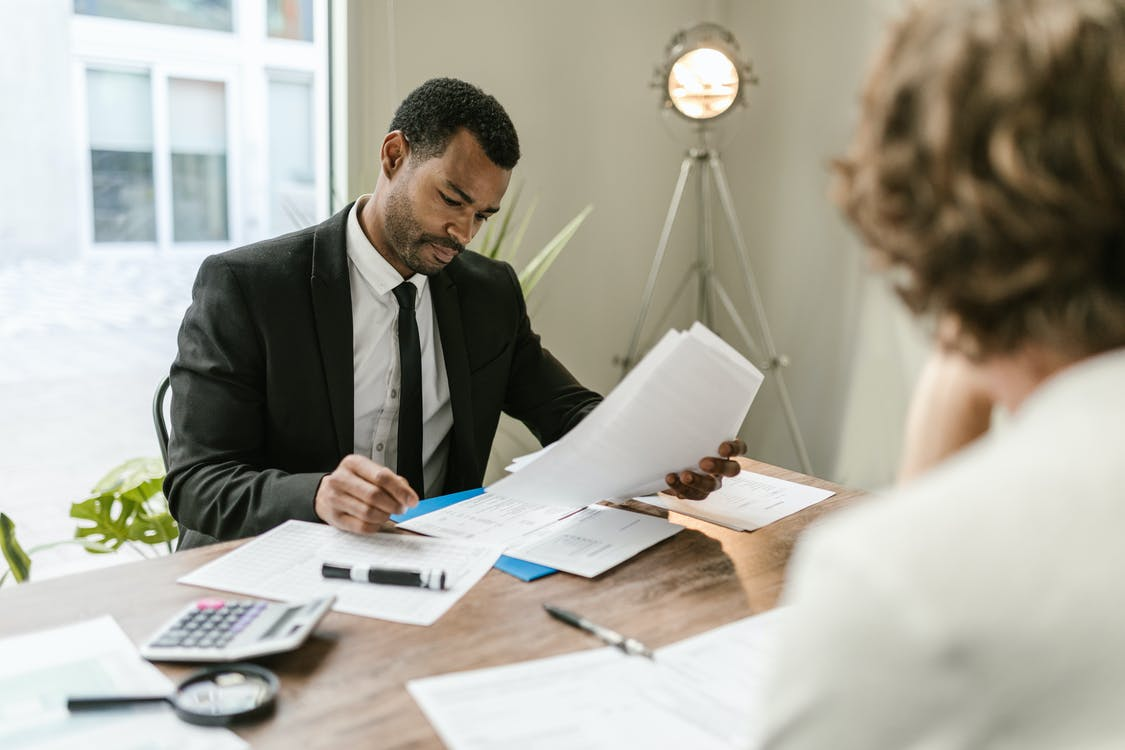
 

Tax accountant with a client

What’s a Tax Deduction?

Tax deductions help lower the taxable income for the year. You can either claim the standard deduction or itemize the deductions. Standard deductions are the ones taxpayers can claim automatically, depending on their filing status. A married couple filing a joint tax return is considered one of the largest standard deductions. Conversely, itemizing refers to listing individual expenses you’d want to write off on the return. Itemizing typically makes sense when the total deductible expenses are higher than the standard deductions.


Some of the above-the-line and itemized deductions include mortgage loan interest, charitable donations, dental and medical expenses, contributions to health saving accounts or traditional IRAs, property and real estate taxes, educator expenses deduction, job search expenses, and more. Above-the-line deductions can be claimed separately even if you’re not itemizing the deductions. However, the ability to claim some deductions could be limited depending on factors like household income and filing status.


Tax brackets determine the tax rate paid on various chunks of the income. When the marginal tax system increased tax rates as income rises, tax deductions could lead to higher savings for those with higher incomes. Professional tax planning consultants at Nidhi Jain CPA can help you determine whether you should itemize deductions or take the standard deductions by comparing your allowable itemized deductions to the standard deduction amount.

Our tax accountants are CTC-certified and can help you with your tax filing chores while helping you limit your tax liabilities in several ways. We offer various tax preparation and advisory services for personal or business tax filing in Bay Area. People across the US rely on us for comprehensive bay area bookkeeping and accounting services, tax resolution services, payroll services, business formation, and back tax solutions.

You can also call or email us to discover how our cloud-based solutions and cutting-edge AccountantWS software can help you achieve your financial goals while remaining compliant cost-effectively.
Related Blogs

This photo shows some tax documents on a table.

Choosing a business structure is an important decision for entrepreneurs because the entity selected can influence taxation, reporting, ownership, and ongoing compliance responsibilities. An LLC, S corporation, and C corporation each have different characteristics, and the right choice depends on the business’s circumstances rather than simply choosing the structure with the lowest potential tax burden.

This blog explains key tax and operational considerations business owners should review when evaluating an entity structure, including income, business goals, growth plans, and compliance responsibilities.

Understanding the LLC Structure

A limited liability company, or LLC, is a flexible business structure commonly used by small and growing businesses. For federal tax purposes, an LLC may receive different tax treatment depending on factors such as the number of owners and elections made by the business.

Flexibility

LLCs generally offer flexibility in management and ownership arrangements, which can make them attractive to entrepreneurs with different business models.

Tax Treatment

An LLC may be taxed in different ways depending on its circumstances. Business owners should evaluate how the chosen tax treatment fits their income and future plans rather than assuming one approach is automatically best.

Understanding an S Corporation

An S corporation is a tax designation available to eligible businesses that meet specific requirements. S corporation taxation generally allows business income to pass through to shareholders rather than being taxed at the corporate level in the same manner as a C corporation.

Ownership Requirements

S corporations have eligibility and ownership restrictions that business owners need to understand before selecting this structure.

This photo shows a calculator on top of some documents.

Compensation Considerations

Owners who work for an S corporation may need to consider payroll and reasonable compensation requirements. These responsibilities should be evaluated carefully because they can affect compliance and administrative workload.

Understanding a C Corporation

A C corporation is a separate tax entity that can be appropriate for certain businesses, particularly those with specific growth, investment, or ownership objectives.

Corporate Taxation

C corporations generally pay corporate income tax, and distributions to shareholders can create additional tax considerations. The overall tax impact should therefore be reviewed based on the company’s expected income and plans.

Growth and Investment

Businesses planning significant expansion or seeking certain types of outside investment may consider a C corporation as part of their long-term strategy.

Get Professional Guidance Before Choosing

Nidhi Jain CPA provides tax and accounting services and business tax services to help business owners evaluate their tax considerations and plan around their financial goals. Professional guidance can also support business owners with bookkeeping, tax planning, business tax filing, and other accounting needs as their companies develop.

Contact us to discuss your business structure, tax considerations, and long-term goals so the available options can be evaluated based on your specific circumstances.

This photo shows some tax documents on a table.

Unpaid taxes can become increasingly difficult to manage when they are left unresolved. Interest, penalties, collection notices, and other consequences may add pressure to an already challenging financial situation. Taking action early can help taxpayers  understand what they owe and determine which options may be available based on their circumstances.

In this blog, we will discuss practical steps for addressing back taxes, why ignoring IRS obligations can create additional problems, and when professional tax resolution assistance may be appropriate.

Start by Understanding What You Owe

The first step toward resolving tax debt is determining the amount owed and understanding which tax years are affected. Taxpayers should review IRS notices, previous tax returns, account information, and available payment records. Working with a tax consultant in San Jose can also help taxpayers better understand their outstanding obligations and available options.

If past tax returns were never filed, those returns may need to be addressed before the complete tax situation can be evaluated. Gathering accurate financial information can help establish a clearer picture of the outstanding liability and support more informed tax planning services.

Do Not Ignore IRS Notices

Ignoring IRS correspondence generally does not make an unpaid balance disappear. Notices may explain the amount due, applicable deadlines, and potential collection actions. Responding promptly can give taxpayers more time to understand their circumstances and consider an appropriate response.

Taxpayers who are uncertain about what a notice means may benefit from consulting a professional who provides tax resolution services before taking action.

This photo shows some tax documents on a table.

Review Potential Resolution Options

The appropriate approach to unpaid taxes depends on factors such as the amount owed, income, assets, expenses, filing history, and ability to pay. Depending on the circumstances, taxpayers may be able to explore payment arrangements or other IRS resolution options.

Evaluate Your Ability to Pay

Understanding current income and necessary living expenses can help establish what payment amount may be manageable.

Address Missing Tax Returns

Unfiled returns can complicate an IRS account. Making sure required returns are properly prepared and filed may be an important part of resolving the overall situation.

Consider Professional Tax Resolution Assistance

Taxpayers facing complicated liabilities, multiple years of unpaid taxes, or ongoing IRS collection activity may want professional assistance in reviewing their options.

Why Professional Guidance Can Help

Nidhi Jain CPA can help individuals understand their tax obligations and work toward addressing unresolved tax matters. Support can include reviewing tax records, helping taxpayers understand their outstanding liabilities, discussing available tax resolution approaches, and assisting with the preparation needed to move forward.

Rather than allowing unpaid taxes to remain unresolved, taxpayers can contact us to discuss their circumstances and determine what professional assistance may be appropriate.

Year-end is an important time for business owners to review their financial position and prepare for upcoming tax obligations. Waiting until tax filing season to examine income, expenses, and business decisions can leave limited time to make changes that may affect the next tax return. Proactive planning can give business owners a clearer understanding of their financial position and help them prepare for the year ahead.

This blog covers several year-end considerations, including reviewing expenses, organizing financial records, evaluating business structure, and preparing for future tax obligations.

Reviewing Business Income and Expenses

One of the first steps in tax planning in the Bay Area is reviewing the business’s income and expenses before the year closes. Comparing current financial results with previous periods can help identify significant changes in revenue, operating costs, and profitability.

Business owners can review whether financial records accurately reflect transactions completed during the year. Missing receipts, incorrectly categorized expenses, or unreconciled accounts can make tax preparation more difficult.

Working with professional bookkeeping and accounting support can help businesses maintain organized records throughout the year and make year-end reviews more efficient.

Evaluating the Business Structure

A business structure can influence how income is reported and how taxes are handled. Business owners who have experienced substantial growth, changes in ownership, or changes in their operations may want to review whether their current structure continues to suit their circumstances.

tax strategy

Factors to Review

Before making structural changes, business owners can consider:

Business Growth

Changes in revenue, profitability, or the number of owners may affect whether the current structure remains appropriate.

Tax Considerations

Different structures can have different tax treatment and reporting requirements. Reviewing these considerations before year-end can support more informed planning.

Future Business Goals

Expansion, investment, hiring, or changes in ownership may influence future tax and accounting needs.

Prepare for Future Tax Obligations

Year-end planning should not focus solely on the immediate tax return. Business owners can also consider expected income, upcoming expenses, expansion plans, and other financial changes that could affect future obligations.

A proactive approach to tax planning services may help identify potential issues earlier and create a clearer financial strategy for the coming year. It can also provide an opportunity to discuss longer-term goals rather than making decisions only around filing deadlines.

Get Professional Guidance Before the Year Ends

Nidhi Jain CPA provides business tax services for businesses seeking organized financial and tax support.

Business owners who want to review their year-end position can contact us to discuss their tax planning needs and prepare for the year ahead.