A Complete Guide to Business Insurance Planning

Business tax payment deadlines

As a dedicated business owner, you have poured your heart, soul, and resources into starting a successful startup. However, unforeseen risks and challenges can arise at any time, threatening your hard-earned achievements. That’s where business insurance planning becomes indispensable. Business insurance is a critical risk management tool designed to protect your company from potential losses due to various perils, such as property damage, liability claims, employee-related risks, and disruptions to your operations.

In this comprehensive guide, we will explore the essential aspects of business insurance planning tailored specifically for SME owners like you.

Understanding Business Insurance

Business insurance plays a pivotal role in safeguarding your SME’s future and ensuring its continued growth. It is a strategic risk management tool that allows you to transfer potential risks to an insurance provider, mitigating the financial impact of adverse events.
 An entrepreneur learning about different business insurance plans

Identifying Insurance Needs

The first step in business insurance planning involves a thorough assessment of your specific risks and coverage requirements. Collaborate with a knowledgeable insurance professional to conduct a comprehensive risk analysis for your accounting practice. Key areas to consider include:

  1. Professional Liability Insurance: You must prioritize professional liability insurance, also known as errors and omissions (E&O) insurance. This coverage protects you from claims of negligence, errors, or omissions arising from your professional services.
  2. General Liability Insurance: Shield your startup against third-party bodily injury, property damage claims, and associated legal expenses through general liability insurance.
  3. Property Insurance: Protect your office space, equipment, and valuable assets with property insurance to recover from physical perils such as fire, theft, or natural disasters.
  4. Cyber Liability Insurance: In today’s digital world, cyber threats are a significant concern. Cyber liability insurance will safeguard your practice from data breaches, cyberattacks, and associated liabilities.
  5. Business Interruption Insurance: Ensure the continuity of your startup in the event of unexpected disruptions, such as a fire or natural disaster, which could temporarily halt business operations.

Selecting the Right Insurance Policies

Once you have identified your insurance needs, the next step is to choose the right policies. Work closely with an experienced business insurance and tax planner who specializes in serving startups and similar businesses. Ensure that the policies you select are tailored to your specific risks and provide adequate coverage limits.

Evaluating Policy Exclusions and Limitations

Carefully review the exclusions and limitations of each insurance policy. Some risks might not be covered by standard policies, and additional endorsements or riders may be necessary to bridge these gaps. Collaborate with your insurance agent to customize your coverage accordingly.

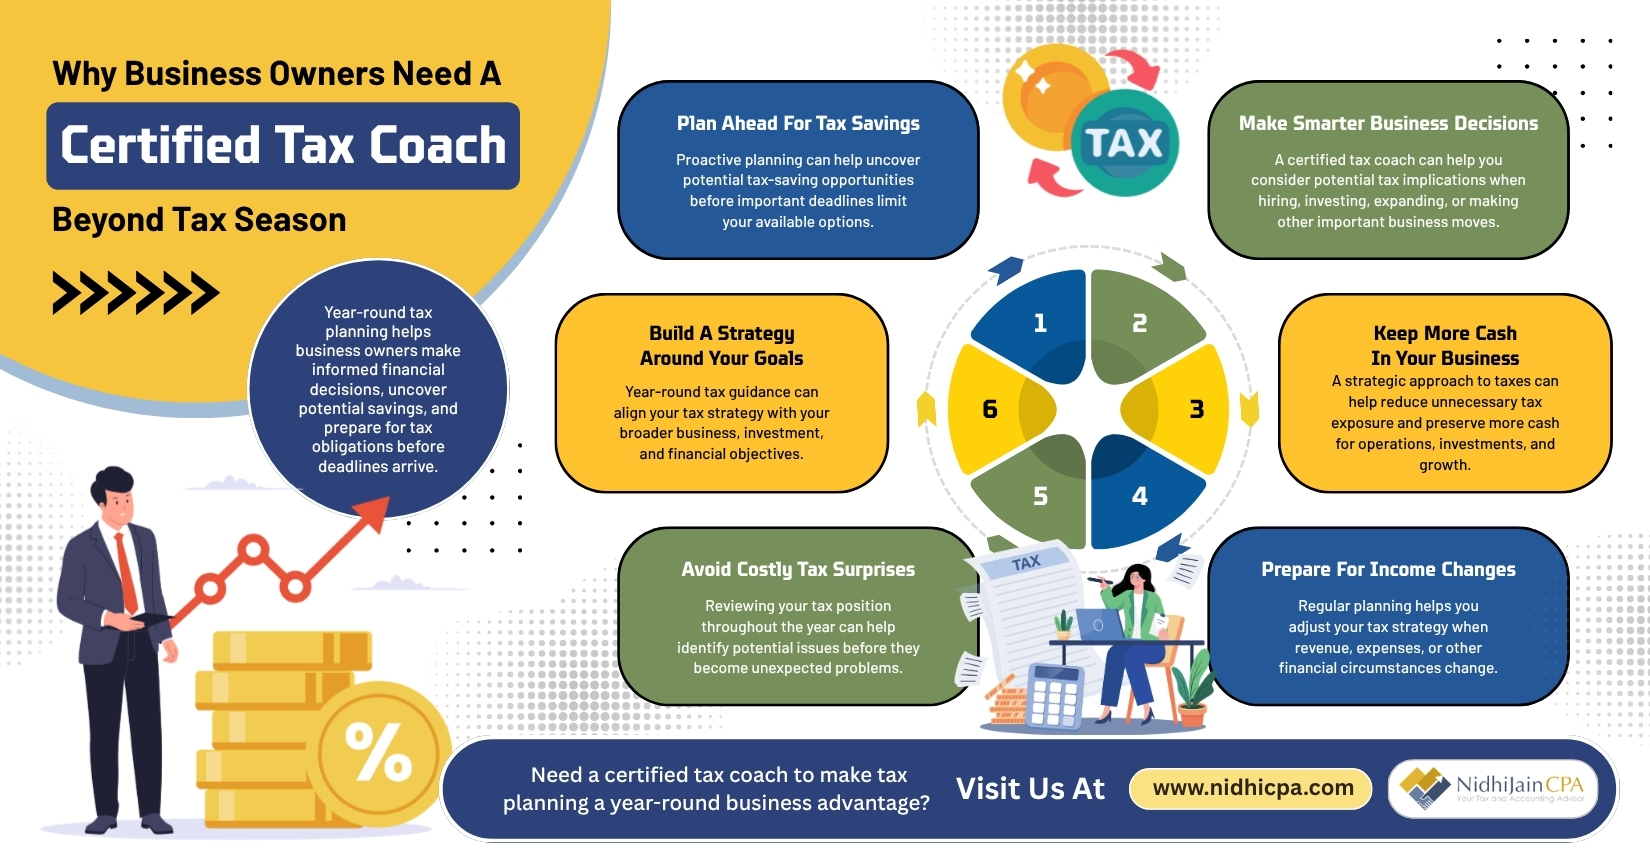
Say goodbye to overpaying in taxes and hello to financial freedom. Nidhi Jain CPA is an expert tax advisor and international tax accountant in Bay Area, ready to optimize your tax strategy, saving you hundreds and thousands of dollars annually. Whether you’re a business owner in San Jose or an individual in Dublin or San Francisco, our and individual tax filing Bay Area have got you covered.

Take charge of your finances and invest in your dreams. Contact us now and watch your wealth grow!
Related Blogs

This photo shows some tax documents.

Receiving an IRS notice showing a tax balance can be stressful, particularly when paying the full amount is not financially realistic. Ignoring the balance, however, does not make the liability disappear. Interest and applicable penalties can continue to accrue until the amount is paid.

This guide explains what taxpayers should organize before requesting an arrangement, what payment options may be available, and how IRS payment plan help can make the process easier to navigate.

Start by Understanding What You Owe

Before requesting a payment arrangement, review your IRS notices and determine the tax year, outstanding balance, penalties, and interest involved. Your IRS Online Account can provide information about your current balance and payment history.

If you have unfiled returns, address those obligations as well. Generally, taxpayers must be current with required filings before certain payment plans can be considered.

Prepare the Information the IRS May Need

Having your financial information organized before applying can make the process more manageable.

Gather Your Tax Records

Keep copies of relevant tax returns, IRS notices, previous payment records, and correspondence together. This gives you a clearer picture of the liability you are trying to resolve.

This photo shows some tax documents.

Review Your Income

Collect recent information showing wages, self-employment income, investment income, or other sources of money you receive. Accurate income information can be important when determining what payment arrangement may be appropriate.

Document Your Regular Expenses

Review housing, utilities, transportation, insurance, food, medical expenses, debt payments, and other recurring costs. Some situations may require additional financial information or collection forms.

Do Not Wait Until Collection Problems Escalate

Addressing an unpaid balance promptly gives you more opportunity to understand available options. If you cannot pay everything immediately, paying what you can and exploring an arrangement may be preferable to simply ignoring the liability.

Professional tax resolution services can also help taxpayers review their circumstances and understand potential approaches for addressing outstanding liabilities.

Get Help Addressing an Outstanding Tax Balance

Tax debt can involve more than simply choosing a monthly payment amount. Nidhi Jain CPA provides back tax solution support, tax planning, and accounting guidance to help taxpayers understand their obligations and work toward addressing outstanding balances.

If you need a tax advisor in the Bay Area for an unresolved tax matter, contact Nidhi Jain CPA to discuss your situation.

This photo shows some tax documents on a table.

Choosing a business structure is an important decision for entrepreneurs because the entity selected can influence taxation, reporting, ownership, and ongoing compliance responsibilities. An LLC, S corporation, and C corporation each have different characteristics, and the right choice depends on the business’s circumstances rather than simply choosing the structure with the lowest potential tax burden.

This blog explains key tax and operational considerations business owners should review when evaluating an entity structure, including income, business goals, growth plans, and compliance responsibilities.

Understanding the LLC Structure

A limited liability company, or LLC, is a flexible business structure commonly used by small and growing businesses. For federal tax purposes, an LLC may receive different tax treatment depending on factors such as the number of owners and elections made by the business.

Flexibility

LLCs generally offer flexibility in management and ownership arrangements, which can make them attractive to entrepreneurs with different business models.

Tax Treatment

An LLC may be taxed in different ways depending on its circumstances. Business owners should evaluate how the chosen tax treatment fits their income and future plans rather than assuming one approach is automatically best.

Understanding an S Corporation

An S corporation is a tax designation available to eligible businesses that meet specific requirements. S corporation taxation generally allows business income to pass through to shareholders rather than being taxed at the corporate level in the same manner as a C corporation.

Ownership Requirements

S corporations have eligibility and ownership restrictions that business owners need to understand before selecting this structure.

This photo shows a calculator on top of some documents.

Compensation Considerations

Owners who work for an S corporation may need to consider payroll and reasonable compensation requirements. These responsibilities should be evaluated carefully because they can affect compliance and administrative workload.

Understanding a C Corporation

A C corporation is a separate tax entity that can be appropriate for certain businesses, particularly those with specific growth, investment, or ownership objectives.

Corporate Taxation

C corporations generally pay corporate income tax, and distributions to shareholders can create additional tax considerations. The overall tax impact should therefore be reviewed based on the company’s expected income and plans.

Growth and Investment

Businesses planning significant expansion or seeking certain types of outside investment may consider a C corporation as part of their long-term strategy.

Get Professional Guidance Before Choosing

Nidhi Jain CPA provides tax and accounting services and business tax services to help business owners evaluate their tax considerations and plan around their financial goals. Professional guidance can also support business owners with bookkeeping, tax planning, business tax filing, and other accounting needs as their companies develop.

Contact us to discuss your business structure, tax considerations, and long-term goals so the available options can be evaluated based on your specific circumstances.