Blogs

This photo shows some tax documents on a table.

Unpaid taxes can become increasingly difficult to manage when they are left unresolved. Interest, penalties, collection notices, and other consequences may add pressure to an already challenging financial situation. Taking action early can help taxpayers  understand what they owe and determine which options may be available based on their circumstances.

In this blog, we will discuss practical steps for addressing back taxes, why ignoring IRS obligations can create additional problems, and when professional tax resolution assistance may be appropriate.

Start by Understanding What You Owe

The first step toward resolving tax debt is determining the amount owed and understanding which tax years are affected. Taxpayers should review IRS notices, previous tax returns, account information, and available payment records. Working with a tax consultant in San Jose can also help taxpayers better understand their outstanding obligations and available options.

If past tax returns were never filed, those returns may need to be addressed before the complete tax situation can be evaluated. Gathering accurate financial information can help establish a clearer picture of the outstanding liability and support more informed tax planning services.

Do Not Ignore IRS Notices

Ignoring IRS correspondence generally does not make an unpaid balance disappear. Notices may explain the amount due, applicable deadlines, and potential collection actions. Responding promptly can give taxpayers more time to understand their circumstances and consider an appropriate response.

Taxpayers who are uncertain about what a notice means may benefit from consulting a professional who provides tax resolution services before taking action.
This photo shows some tax documents on a table.

Review Potential Resolution Options

The appropriate approach to unpaid taxes depends on factors such as the amount owed, income, assets, expenses, filing history, and ability to pay. Depending on the circumstances, taxpayers may be able to explore payment arrangements or other IRS resolution options.

Evaluate Your Ability to Pay

Understanding current income and necessary living expenses can help establish what payment amount may be manageable.

Address Missing Tax Returns

Unfiled returns can complicate an IRS account. Making sure required returns are properly prepared and filed may be an important part of resolving the overall situation.

Consider Professional Tax Resolution Assistance

Taxpayers facing complicated liabilities, multiple years of unpaid taxes, or ongoing IRS collection activity may want professional assistance in reviewing their options.

Why Professional Guidance Can Help

Nidhi Jain CPA can help individuals understand their tax obligations and work toward addressing unresolved tax matters. Support can include reviewing tax records, helping taxpayers understand their outstanding liabilities, discussing available tax resolution approaches, and assisting with the preparation needed to move forward.

Rather than allowing unpaid taxes to remain unresolved, taxpayers can contact us to discuss their circumstances and determine what professional assistance may be appropriate.
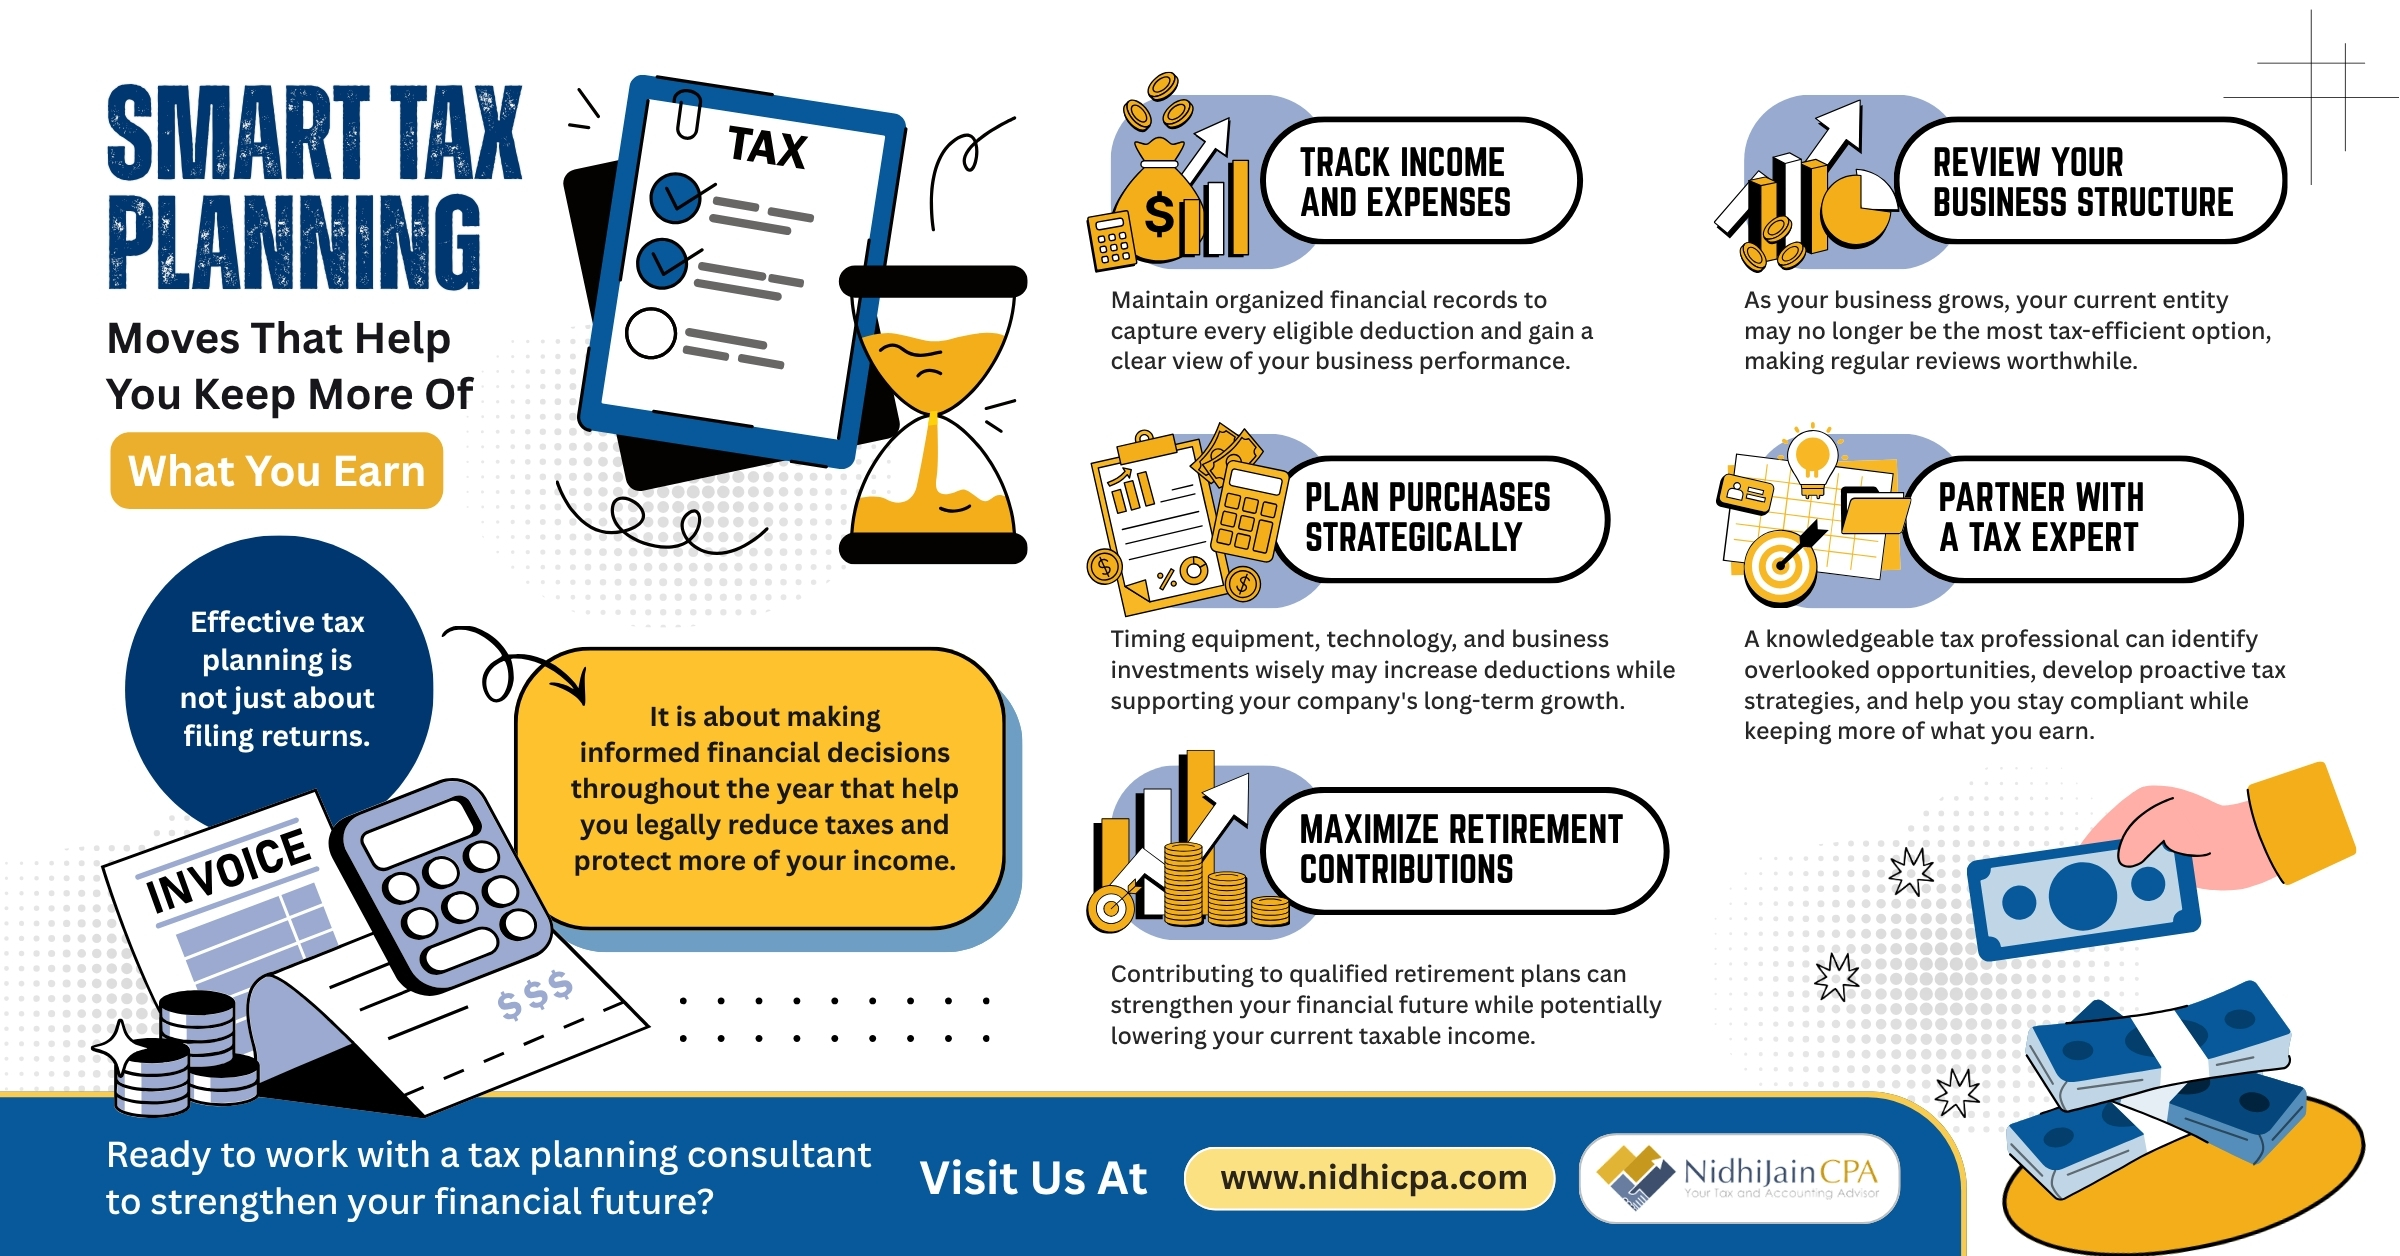
Year-end is an important time for business owners to review their financial position and prepare for upcoming tax obligations. Waiting until tax filing season to examine income, expenses, and business decisions can leave limited time to make changes that may affect the next tax return. Proactive planning can give business owners a clearer understanding of their financial position and help them prepare for the year ahead.

This blog covers several year-end considerations, including reviewing expenses, organizing financial records, evaluating business structure, and preparing for future tax obligations.

Reviewing Business Income and Expenses

One of the first steps in tax planning in the Bay Area is reviewing the business’s income and expenses before the year closes. Comparing current financial results with previous periods can help identify significant changes in revenue, operating costs, and profitability.

Business owners can review whether financial records accurately reflect transactions completed during the year. Missing receipts, incorrectly categorized expenses, or unreconciled accounts can make tax preparation more difficult.

Working with professional bookkeeping and accounting support can help businesses maintain organized records throughout the year and make year-end reviews more efficient.

Evaluating the Business Structure

A business structure can influence how income is reported and how taxes are handled. Business owners who have experienced substantial growth, changes in ownership, or changes in their operations may want to review whether their current structure continues to suit their circumstances.

tax strategy

Factors to Review

Before making structural changes, business owners can consider:

Business Growth

Changes in revenue, profitability, or the number of owners may affect whether the current structure remains appropriate.

Tax Considerations

Different structures can have different tax treatment and reporting requirements. Reviewing these considerations before year-end can support more informed planning.

Future Business Goals

Expansion, investment, hiring, or changes in ownership may influence future tax and accounting needs.

Prepare for Future Tax Obligations

Year-end planning should not focus solely on the immediate tax return. Business owners can also consider expected income, upcoming expenses, expansion plans, and other financial changes that could affect future obligations.

A proactive approach to tax planning services may help identify potential issues earlier and create a clearer financial strategy for the coming year. It can also provide an opportunity to discuss longer-term goals rather than making decisions only around filing deadlines.

Get Professional Guidance Before the Year Ends

Nidhi Jain CPA provides business tax services for businesses seeking organized financial and tax support.

Business owners who want to review their year-end position can contact us to discuss their tax planning needs and prepare for the year ahead.

This photo shows some tax documents on a table.

Many small businesses begin by managing their finances with spreadsheets, accounting software, or informal recordkeeping. This approach may work when transactions are limited, but as businesses grow, bookkeeping often becomes too time-consuming and complicated to manage alone. Accurate financial records are important not only for tax filing but also for understanding cash flow, expenses, profitability, and future business decisions.

This blog covers key signs that a business may need professional bookkeeping, including reconciliation challenges, financial reporting demands, accounts payable, and maintaining organized records.

When DIY Bookkeeping Starts Taking Too Much Time

Bookkeeping can become difficult to manage as a business adds customers, vendors, bank accounts, expenses, and financial transactions. Business owners who spend hours every week entering transactions or correcting records may be taking valuable time away from operations and growth.

A growing company may benefit from professional bookkeeping and accounting when financial tasks begin interfering with core responsibilities. Professional support can help keep records organized while giving business owners more time to focus on clients and strategic priorities.

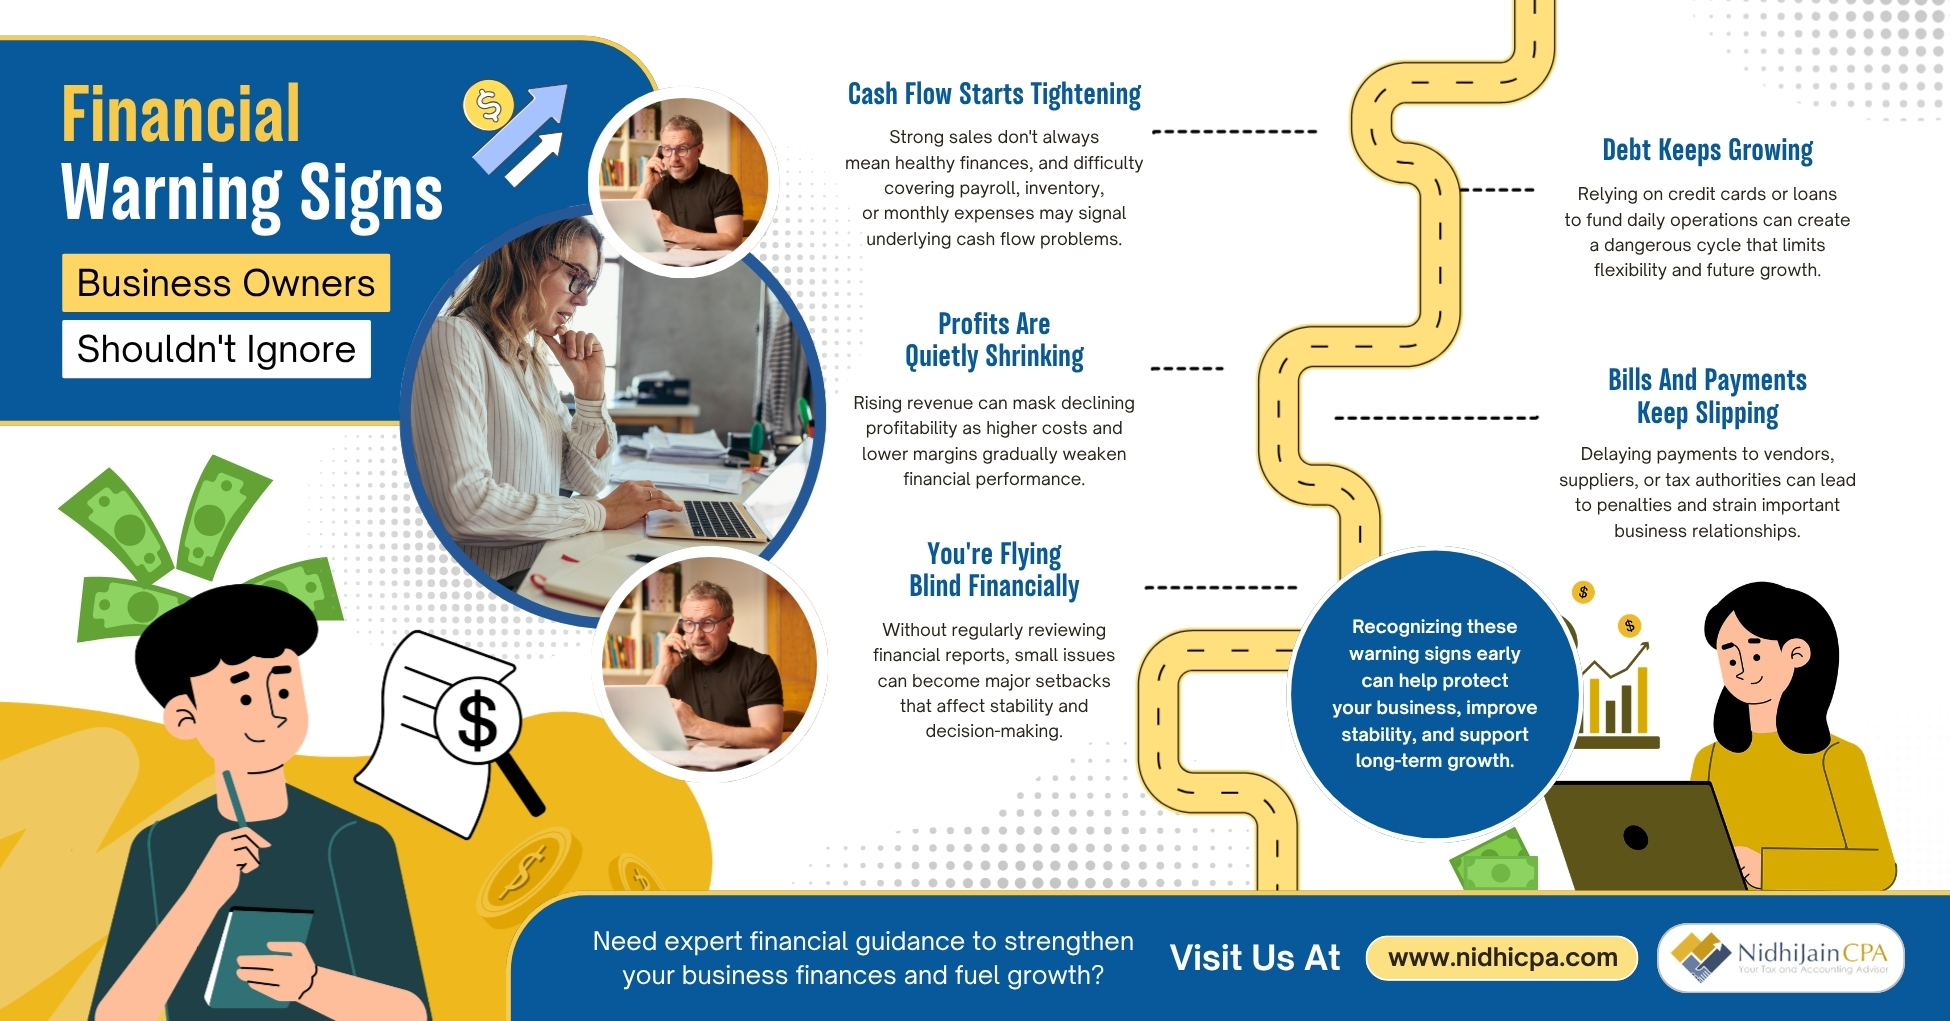
Signs Your Business Has Outgrown DIY Bookkeeping

Several warning signs can indicate that a business has reached the point where additional bookkeeping support would be beneficial.

Bank Reconciliations Are Falling Behind

Bank and credit card accounts should be reconciled regularly so that financial records accurately reflect actual transactions. When reconciliations are delayed, or unexplained differences continue appearing, it may be time to consider professional bookkeeping in the Bay Area.


Financial Reports Are Difficult to Understand

Financial statements can provide valuable insight into revenue, expenses, profitability, and cash flow. If reports are incomplete, outdated, or difficult to interpret, professional bookkeeping support can help create more reliable information for decision-making.

Accounts Payable Is Becoming Disorganized

As a company grows, the number of vendors and bills may increase. Missing invoices, late payments, and unclear payment records can create unnecessary financial stress. Organized bookkeeping can help businesses maintain better visibility into outstanding obligations.

Records Are Not Ready for Tax Filing

Business owners should maintain accurate records throughout the year rather than trying to reconstruct transactions when tax deadlines approach. Professional bookkeeping can help keep financial information organized for business tax filing needs and make tax preparation more efficient.

When Professional Support Makes Sense

Nidhi Jain CPA provides professional bookkeeping and accounting support designed to help businesses maintain accurate records while staying focused on their operations and long-term growth.

Businesses that are spending too much time managing spreadsheets, falling behind on reconciliations, or struggling to understand their financial records can contact us to discuss bookkeeping and accounting needs and determine what level of professional support may be appropriate.
photo showing a person showing a document to two elderly people

Earning income from outside the United States can introduce additional considerations when preparing a U.S. tax return. U.S. citizens and resident taxpayers are generally subject to U.S. federal income tax on worldwide income, meaning certain foreign earnings and financial interests may need to be reported even when the income was earned outside the country. Understanding these responsibilities can help taxpayers avoid missed reporting requirements and unexpected tax issues. …

Laptop, notebook, and printed financial reports arranged on an office desk

Tax trouble often starts months before a return is due. A missed receipt, unreconciled bank account, or incorrect expense category can distort taxable income. The IRS generally suggests keeping tax records for three years, while employment tax records should be kept for at least four years.

That is why business bookkeeping should be handled every month, not rebuilt at year-end. A short monthly routine gives owners cleaner reports, better cash flow visibility, and stronger support for deductions.

Reconcile Every Financial Account

Compare each bank, credit card, loan, and payment processor balance with the bookkeeping system. Investigate missing deposits, duplicate charges, fees, returned payments, and transfers.

Complete this task before closing the month. Otherwise, errors can carry into future reports and make taxable profit look higher or lower than it is.

Record and Categorize Expenses

Enter every business purchase with the correct date, vendor, amount, and category. Save the receipt or invoice with the transaction.

Pay close attention to:

  • Software subscriptions
  • Insurance premiums
  • Travel and mileage
  • Advertising costs
  • Professional fees
  • Equipment purchases

Repairs, supplies, and equipment may receive different tax treatment. A certified public accountant can help set up categories that support accurate bookkeeping and accounting.

Review Receivables and Payables

Run an accounts receivable report each month. Follow up on overdue invoices and record customer payments correctly. Then review unpaid vendor bills and due dates.

Calculator and pen placed on printed business charts and financial reports

This helps owners distinguish revenue earned from cash collected. It also shows how much cash is committed to bills, loan payments, and taxes.

Check Tax Accounts

Confirm wages, employer taxes, benefits, reimbursements, and contractor payments.

Also review sales tax and estimated tax accounts. These balances should not be treated as available operating cash. Monthly checks make it easier to find missing payments before deadlines.

Run Key Financial Reports

Review the profit and loss statement, balance sheet, and cash flow report. Compare the current month with the prior month, budget, and same period last year.

Look for sharp changes in sales, margins, debt, or operating costs. Ask your CPA in Bay Area about entries that do not match business activity.

Create a Monthly Closing Checklist

Use the same steps every month and assign a completion date. Consistency reduces rushed corrections during filing season.

Keep Your Books Tax-Ready With Nidhi Jain CPA

Nidhi Jain CPA provides business bookkeeping support for owners who need organized records and clear financial reports. Our bookkeeping and accounting services include reconciliations, expense reviews, and monthly reporting. Work with our certified public accountant who can help keep your records ready for tax filing all year. Contact us now.

The United States has 36.2 million small businesses, and they employ 62.3 million people, according to the U.S. Small Business Administration.

That means millions of owners make tax, debt, and investment decisions every day. Yet many speak with a CPA only when a return is due. By then, a missed payment, weak bookkeeping process, or poorly timed purchase may be difficult to correct. Asking the right financial questions before hiring a CPA can help you find someone who supports compliance and better decisions.

What Is My Real Cash Flow Position?

Profit does not always equal cash in the bank. Ask the CPA to explain how much cash remains after loan payments, owner withdrawals, taxes, and overdue invoices.

Request a monthly cash flow forecast. It should show expected receipts, fixed bills, tax payments, and periods when cash may become tight. This helps you decide when to hire, buy equipment, or delay spending.

Are My Books Ready for Tax Filing?

Ask how often bank, credit card, loan, and payment processor accounts should be reconciled. Also ask who will review uncategorized transactions, owner payments, and unpaid invoices.

Good bookkeeping should produce a profit and loss statement and balance sheet that agree with supporting records. A certified public accountant in Bay Area should also explain which documents must be kept for deductions.

Financial professional discussing a printed report with a business owner

Am I Paying Enough Tax During the Year?

Federal income tax generally follows a pay-as-you-go system. Business owners may need withholding or estimated payments during the year.

Ask your CPA to recalculate payments when revenue, deductions, or owner income changes. Tax planning should also cover retirement contributions, asset purchases, credits, and the timing of income and expenses.

Does My Business Structure Still Fit?

The SBA states that business structure affects taxes, operations, and personal asset exposure.

Ask how your sole proprietorship, partnership, LLC, S corporation, or C corporation affects owner pay, filing costs, and state taxes. An entity change may add fees and reporting duties, so compare the full annual cost before making a decision.

What Should I Prepare for Next?

Ask for a 12-month plan covering hiring, financing, expansion, estimated taxes, retirement contributions, and major purchases. Also ask how often you will meet and which reports the CPA will provide.

Clear communication matters. Confirm which services are included, how quickly questions are answered, and who will handle your account. This helps prevent confusion when deadlines or major financial decisions arise.

Ask Better Questions With Nidhi Jain CPA

Nidhi Jain CPA helps business owners connect bookkeeping, tax planning, cash flow, and future decisions. Review the financial questions before hiring a CPA with a certified public accountant who can help build a clear financial plan based on your business needs. Contact us now.

Business professional calculating operating costs while reviewing financial documents

Higher operating costs do more than reduce profit. They can also make last quarter’s tax estimate outdated. In the Los Angeles area, consumer prices were 3.3% higher in June 2026 than one year earlier. Energy prices rose 15.1% during the same period, according to the U.S. Bureau of Labor Statistics.

Higher fuel, insurance, rent, inventory, and borrowing costs now compete for the cash needed for taxes. This is where corporate tax planning becomes important. Waiting until filing season may leave little time to correct payments, document expenses, or plan purchases.

Update Tax Projections as Costs Change

Do not rely on a tax estimate prepared at the start of the year. Review revenue, gross margin, financing costs, and operating expenses every quarter.

If profit falls, estimated payments may need adjustment. If revenue rises faster than expenses, the company may need to reserve more cash. Regular tax planning can reduce underpayment risk and avoid unnecessary overpayments.

Record Deductible Expenses Correctly

The IRS generally allows deductions for ordinary and necessary business expenses. However, the timing and treatment of each cost can differ.

Rent, utilities, insurance, software, professional fees, and advertising may be currently deductible. Major improvements, equipment, and certain startup costs may need to be capitalized or deducted over time.

Hand holding a pen over a printed business expense report with financial charts

Keep records showing the amount, date, vendor, and business purpose. A tax planning consultant can help separate repairs from improvements and business costs from personal spending.

Review the Tax Cost of Financing

Higher interest rates increase the cost of loans for equipment, inventory, and expansion. Business interest is often deductible, but Section 163(j) may limit the amount some taxpayers can claim in the current year. Disallowed interest may need to be carried forward.

Before taking on debt, compare the after-tax interest cost with expected cash flow. Corporate tax planning should account for deduction limits, loan terms, and future payment pressure.

Time Equipment Purchases With Care

A tax deduction should not be the only reason to buy an asset. Confirm that the purchase supports operations and fits the budget. Then review the placed-in-service date, Section 179 eligibility, first-year depreciation, and future deduction needs.

Tax planning services can compare an immediate write-off with deductions spread across later years.

Control Rising Costs With Nidhi Jain CPA

Nidhi Jain CPA provides corporate tax planning for companies facing higher expenses and financing costs. Work with a tax planning consultant to review deductions, estimated payments, asset purchases, and cash needs before filing deadlines limit your options.

Contact our dedicated tax planning consultant from Nidhi Jain CPA.

Borrowing becomes less forgiving when interest rates stay elevated. The Federal Reserve’s H.15 release listed the bank prime loan rate at 6.75% in July 2026. Many business loans are priced in relation to prime, so weak financial records can become costly when lenders review repayment risk closely.

A profitable business may still struggle to qualify for financing if its books are incomplete. Missing invoices, unreconciled accounts, or unclear owner transactions can make cash flow look weaker than it is. Accurate Bay Areabookkeeping services give lenders and a CPA a clearer view of the company’s financial position.

Clean Records Strengthen Loan Applications

Lenders commonly review income statements, balance sheets, cash flow statements, debt obligations, and tax returns. The U.S. Small Business Administration advises established businesses to include historical financial statements when preparing a business plan for financing.

Professional bookkeeping services help ensure that revenue, expenses, assets, and liabilities are recorded consistently. This reduces differences between accounting reports, bank statements, and tax filings. A lender can then assess how much cash the business produces and how much debt it can support.

A bookkeeping consultant holding a pen while working on tax documents using a laptop and calculator

Accurate Books Support Better Refinancing Decisions

Refinancing can lower a payment, change the repayment period, or replace short-term debt. It can also add fees or increase total interest.

Before refinancing, bookkeeping and accounting records should show each loan balance, interest rate, monthly payment, maturity date, and collateral requirement. These details help a certified public accountant compare the current debt with the proposed loan.

Without current records, a business may focus only on the new monthly payment and overlook the full financing cost.

Cash Flow Becomes More Important

High interest charges reduce the cash available for inventory, rent, taxes, and growth. Monthly bookkeeping should track cash collected, upcoming bills, overdue invoices, loan payments, and seasonal changes.

A rolling cash flow forecast can show when the business may face a shortfall. Owners can then follow up on receivables, delay nonessential spending, or discuss financing before cash becomes tight.

Financial Errors Can Affect Loan Terms

Duplicate expenses, missing sales, and incorrect loan entries can distort profit and debt levels. These errors may affect lender ratios or lead to repeated information requests.

Regular reconciliations and monthly reviews help catch problems early. A CPA can also explain unusual changes and prepare records for lender questions.

Build Lender-Ready Records With Nidhi Jain CPA

Nidhi Jain CPA provides bookkeeping in Bay Area for businesses seeking stronger cash flow visibility, financing, or refinancing. Our bookkeeping and accounting support helps organize financial statements, reconcile accounts, and prepare records lenders can review with confidence. Work with our certified public accountant who can connect accurate numbers with informed financing decisions.

Contact us now.

Tax documents, coins, and Tax written on wooden blocks placed on a green surface

Higher prices can reduce profit long before a tax return is due. In the Los Angeles area, consumer prices were 3.3% higher in June 2026 than one year earlier. Energy prices rose 15.1% during the same period, according to the U.S. Bureau of Labor Statistics.

For California business owners, rising fuel, insurance, rent, and financing costs can make yesterday’s tax estimates inaccurate. Waiting until filing season leaves little time to adjust. Year-Round Tax Planning in California gives owners regular chances to protect cash flow, correct payments, and act before important deadlines pass.

Match Estimated Taxes to Current Results

Estimated payments based on last year’s profit may no longer fit the business. A stronger or weaker quarter can change federal and California obligations.

Quarterly tax planning reviews compare current income, deductions, credits, and payments. This can reduce the risk of underpayment penalties. It may also prevent unnecessary overpayments that remove cash from daily operations.

Act Before Deduction Deadlines Pass

Many tax decisions must occur during the tax year. Equipment may need to be placed in service before year-end. Retirement plans and contributions may have separate setup or funding deadlines. Owner compensation and employee benefits may also require action before tax forms are issued.

A tax planning consultant can review planned purchases, depreciation choices, retirement contributions, and expense records while there is still time to act. Filing a return months later cannot recreate a missed deadline.

Tax documents, coins, and Tax written on wooden blocks placed on a green surface

Account for Federal and California Differences

California does not automatically adopt every federal tax change. Senate Bill 711 moved the state’s general conformity date to January 1, 2025. However, federal laws enacted after that date may still receive different California treatment.

These differences can affect deductions, credits, depreciation, and taxable income. Year-Round Tax Planning in California helps businesses track federal and state treatment separately rather than assuming one calculation works for both returns.

Review Decisions Before the Business Changes

Hiring employees, opening another location, buying assets, or selling in new states can create added filing and payment duties. Tax planning services allow these decisions to be reviewed before contracts are signed.

Plan Ahead With Nidhi Jain CPA

Nidhi Jain CPA provides year-round tax planning in California for business owners facing higher costs and changing tax rules. Work with our tax planning consultant to review estimates, deductions, purchases, and filing duties before valuable options expire.

Contact a dedicated tax planning consultant from Nidhi Jain CPA.

According to the Internal Revenue Service, the audit rate for individual tax returns remains relatively low, but businesses can still be selected for review based on factors such as reporting inconsistencies, unusually high deductions, or missing information. An audit does not automatically mean something is wrong. It simply means the IRS wants to verify the information reported on a tax return. …

Submitting paper tax returns is quickly becoming a thing of the past. Today, digital filing is the preferred method for businesses because it is faster, more accurate, and easier to track. According to the Internal Revenue Service, more than 94% of individual tax returns are filed electronically, reflecting the widespread shift toward digital filing across the United States. Electronic filing also allows faster processing and reduces common errors caused by incomplete or inaccurate information.

For small and medium-sized businesses, this shift offers more than convenience. It helps reduce costly filing mistakes, speeds up processing, and keeps financial records better organized throughout the year. If your business tax return filing process still depends on paper documents or last-minute manual entries, it may be time for a better approach.

Fewer Errors Through Automatic Validation

One of the biggest advantages of electronic filing is built-in error checking.

E-filing systems automatically identify issues such as:

  • Missing information
  • Invalid tax identification numbers
  • Mathematical errors
  • Incomplete forms

Correcting these problems before submission reduces the likelihood of rejected returns and processing delays.

Combined with proper tax planning, electronic filing creates a smoother and more accurate filing process.

Faster Processing and Quicker Confirmations

Paper returns often take longer to process because they require manual handling.

With electronic filing:

  • Returns are submitted immediately
  • Filing confirmations are received electronically
  • Processing generally begins sooner

This gives business owners greater confidence that their returns have been successfully received.

A calculator, coins, and US dollars on top of a paper with Taxes written on it

Better Recordkeeping Throughout the Year

Digital filing works best when supported by organized financial records.

Many accounting platforms automatically store:

  • Income records
  • Expense reports
  • Supporting documents
  • Prior tax returns

Having everything in one place simplifies future business tax return filing and reduces time spent searching for paperwork.

Stronger Data Security

Paper files can be misplaced or damaged.

Secure electronic filing systems use encryption and authentication measures to help protect financial information during transmission.

Businesses should also:

  • Use secure passwords
  • Enable multi-factor authentication
  • Back up financial records regularly

These simple steps add another layer of protection for sensitive tax information.

Pair E-Filing With Year-Round Tax Planning

Electronic filing improves the filing process, but it cannot replace proper planning.

Working with tax planning services throughout the year helps businesses:

  • Track deductions
  • Prepare estimated tax payments
  • Organize financial records
  • Reduce filing surprises

A tax planning consultant reviews financial information before filing season, allowing time to correct issues instead of rushing to meet deadlines.

Digital Filing Is More Than Convenience

Electronic filing helps businesses stay organized, improve accuracy, and reduce unnecessary delays. Combined with consistent recordkeeping and regular tax planning, it creates a smoother tax process and supports better financial decisions throughout the year.

Simplify Your Business Tax Return Filing with Nidhi Jain CPA

At Nidhi Jain CPA, we make business tax return filing simple, accurate, and efficient. Our team combines modern electronic filing with year-round tax planning services to help businesses reduce errors, stay compliant, and prepare for future growth.

Contact our dedicated tax planning consultant that works closely with you to organize records, identify tax-saving opportunities, and make every filing season less stressful.

Running a business across state lines has become much easier thanks to remote work, online sales, and digital services. Managing taxes, however, has become much harder. According to reports, more than 36 million small businesses operate in the United States, and many now generate income from customers or employees located in multiple states. At the same time, state tax rules continue to evolve following the South Dakota v. Wayfair, Inc. decision, allowing states to require tax collection based on economic activity instead of physical presence.

For business owners, this creates a common problem. You may be fully compliant in one state while unknowingly creating tax obligations in another. Without proper planning, this can lead to unexpected tax bills, penalties, and unnecessary stress.

Working with a tax advisor for multi-state businesses helps you stay ahead of these challenges before they become costly.

Understand Where Your Business Has Tax Nexus

The first step is determining where your business has tax obligations.

A tax nexus may be created through:

  • Employees working remotely
  • Warehouses or inventory
  • Sales that exceed a state’s economic threshold
  • Temporary business operations or projects

Each state sets its own rules. Meeting a filing requirement in one state does not automatically satisfy another.

Proper tax planning begins by identifying every state where your business has filing responsibilities.

Track Income by State

Businesses operating in multiple states should maintain detailed records of revenue earned in each location.

Accurate reporting helps:

  • Allocate income correctly
  • Avoid double taxation
  • Support state tax filings if questions arise

Waiting until year-end often results in incomplete records and time-consuming corrections.

Monitor Remote Employees Carefully

A single remote employee can create business tax obligations in another state.

This may require:

  • State payroll tax withholding
  • Employer registration
  • Additional business tax filings

A tax planning consultant reviews your workforce structure and identifies new filing requirements before deadlines arrive.

A smiling man talking on a phone while working remotely from home

Stay Current on State Tax Law Changes

Tax rules change regularly.

States may update:

  • Filing thresholds
  • Tax rates
  • Sales tax requirements
  • Nexus standards

Regular reviews help ensure your business remains compliant as regulations change.

This is one of the biggest advantages of working with tax planning services instead of waiting until tax season.

Maintain Consistent Financial Records

Clean financial records simplify multi-state reporting.

Keep documentation for:

  • Revenue by state
  • Payroll records
  • Business expenses
  • Sales tax collected

Good recordkeeping reduces filing errors and supports your position if a state requests additional information.

Plan Ahead Instead of Reacting

Multi-state taxation becomes more complicated as businesses grow.

Opening a new office, hiring remote employees, or expanding into another market can all create additional tax responsibilities.

A tax advisor for multi-state businesses reviews these decisions before they happen, helping reduce compliance risks and avoid unnecessary costs.

Keep Your Business Compliant with Nidhi Jain CPA

Expanding into new markets should create new opportunities, not unexpected tax problems. At Nidhi Jain CPA, our tax advisor for multi-state businesses works closely with business owners to identify filing obligations, support year-round tax planning, and provide dependable tax planning services for growing companies.

Contact our dedicated tax planning consultant that helps you stay compliant while reducing tax risks across multiple states.

Many small businesses no longer operate from just one location or through one sales channel. Today, a business might sell products in a physical store, through its own website, on online marketplaces, and even through social media. According to the U.S. Census Bureau, U.S. retail e-commerce sales, adjusted for seasonal variation, reached over $326 billion during the first quarter of 2026, showing that online sales continue to account for a significant share of business revenue.

While multiple sales channels create more opportunities, they also make hybrid business bookkeeping much more challenging. Tracking payments from different platforms, managing invoices, and reconciling bank deposits can quickly become overwhelming if records are not organized properly.

The good news is that a few simple bookkeeping habits can make managing both online and offline revenue much easier.

Keep Every Sales Channel Separate

One of the biggest mistakes hybrid businesses make is combining all sales into one category.

Instead, record revenue separately for:

  • In-store sales
  • Website orders
  • Marketplace sales
  • Social media transactions

This makes it easier to measure performance and identify which channels generate the highest revenue.

Good bookkeeping and accounting begins with accurate categorization.

Reconcile Digital Payments Regularly

Many businesses receive payments through:

  • Credit card processors
  • Digital wallets
  • Online payment platforms
  • Bank transfers

These services often deduct transaction fees before deposits reach your bank account.

A bookkeeping consultant holding a pen while working on tax documents using a laptop and calculator

Reconciling payment reports with bank deposits every week helps ensure:

  • Sales match deposits
  • Processing fees are recorded correctly
  • Missing transactions are identified quickly

This reduces errors before month-end.

Track Outstanding Invoices

Hybrid businesses often work with both immediate payments and invoiced customers.

Create a routine to monitor:

  • Unpaid invoices
  • Due dates
  • Partial payments
  • Late balances

Following up on overdue invoices improves cash flow and prevents revenue from slipping through the cracks.

Accurate bookkeeping gives you a clear picture of what has been earned versus what has actually been collected.

Record Refunds and Returns Correctly

Returns are a normal part of business, especially for online sales.

Refunds should never simply reduce your bank balance without proper documentation.

Maintain records for:

  • Original sale
  • Refund amount
  • Reason for return

This keeps financial reports accurate and prevents overstated revenue.

Use One Accounting System for Every Channel

Managing separate spreadsheets for online and offline sales often creates duplicate entries and reporting errors.

Instead, use one accounting platform that connects all revenue sources into a single dashboard.

This improves:

  • Financial reporting
  • Inventory tracking
  • Month-end reconciliation

It also simplifies hybrid business bookkeeping throughout the year.

Review Financial Reports Every Month

Do not wait until tax season to review your numbers.

Monthly reports help you:

  • Compare revenue across channels
  • Identify unusual expenses
  • Monitor cash flow
  • Correct bookkeeping errors early

Consistent reviews support better business decisions and reduce year-end stress.

Simplify Hybrid Business Bookkeeping with Nidhi Jain CPA

Managing multiple revenue streams does not have to become a bookkeeping challenge. At Nidhi Jain CPA, we help businesses build organized hybrid business bookkeeping systems that accurately track online and offline sales. Our bookkeeping and accounting services help business owners stay organized, improve cash flow visibility, and prepare accurate financial records throughout the year.

Contact us now.