
Starting a business is exciting, but taxes can feel like a challenge if you’re new to the process. This startup tax guide outlines everything you need to know about tax obligations, deductions, and credits for startups in 2025, helping you save money and avoid costly mistakes.
Choosing the Right Business Entity
Your business structure and expenses significantly impact your taxes. Here are the main options:
- Sole Proprietorship:The simplest structure, where business income is reported on your personal tax return. However, you’re responsible for self-employment tax.
- Partnership:Profits and tax responsibilities are shared among partners, and each partner files taxes on their share of the income.
- LLC (Limited Liability Company):Offers liability protection and lets you choose how you’re taxed—either as a partnership or corporation.
- Corporation:Separates personal assets from the business, subjecting profits to corporate taxes but offering benefits like reinvestment options.
Consulting a tax advisor helps you choose the right structure to meet your goals and minimize tax burdens.
Key Tax Obligations for Startups
Every entrepreneur must meet these tax requirements:
- Federal Income Tax: Filed annually based on your business’s profits.
- State Taxes:Each state has different rules; ensure compliance by registering your business properly.
- Self-Employment Tax:For sole proprietors and partners, this covers Social Security and Medicare.
- Estimated Taxes:Pay quarterly if you expect to owe $1,000 or more in federal taxes.
Engaging with professional bookkeeping and accounting services ensures your financial records are precise and ready for tax season.
Tax Credits and Deductions
Take advantage of these tax-saving opportunities to reduce your startup costs:
- Startup Cost Deductions:Deduct up to $5,000 in expenses related to launching your business.
- Research and Development (R&D) Credits:A great option for tech and innovation-focused startups.
- Work Opportunity Tax Credit:Receive credits for hiring employees from eligible groups.
- Home Office Deduction:If you work from home, a portion of your rent, utilities, and internet can be deducted.
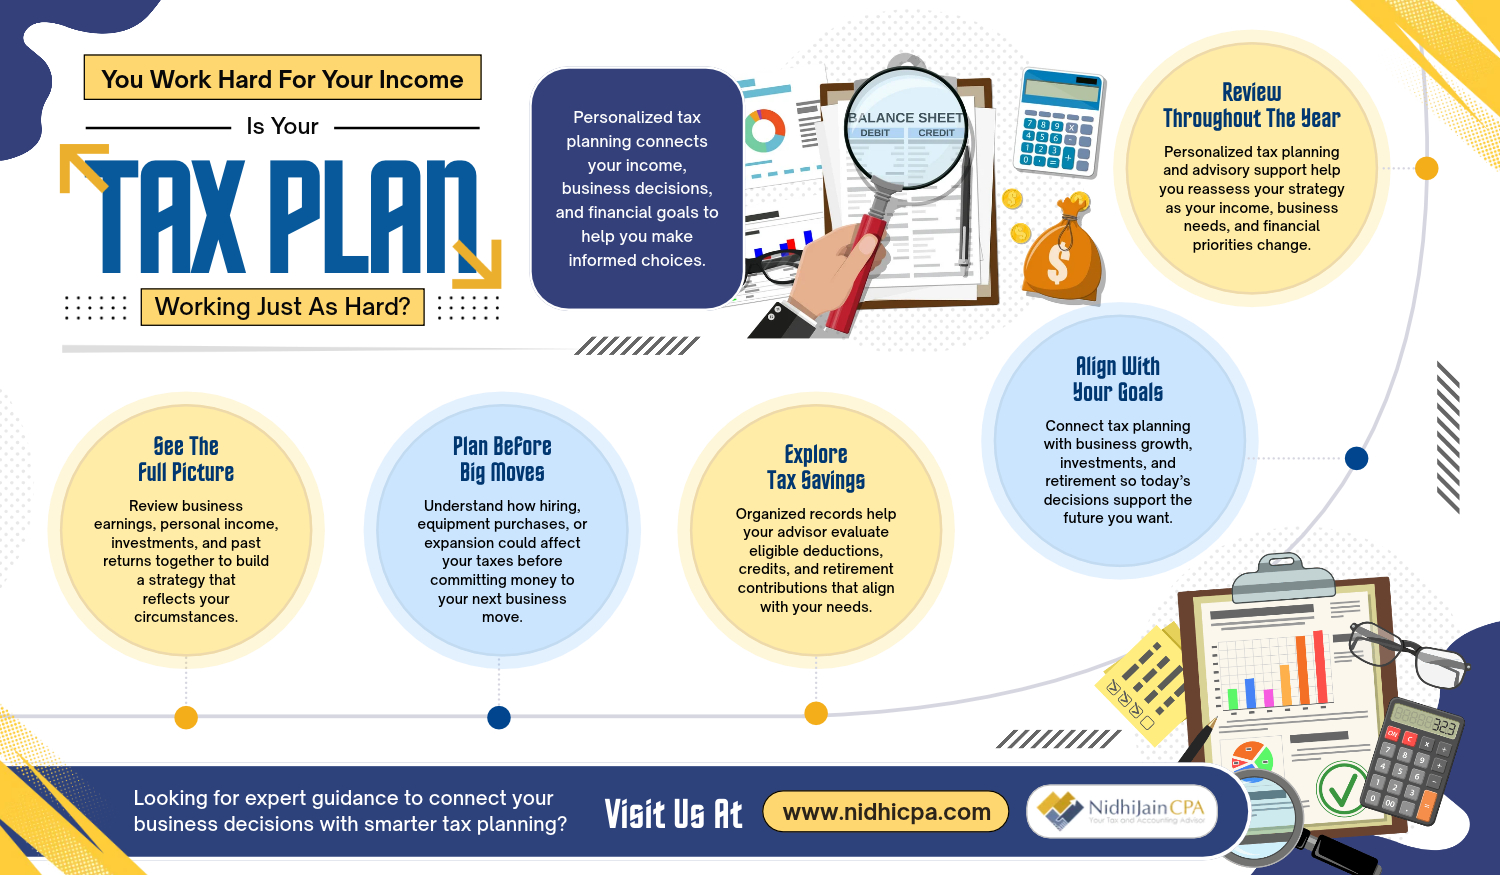
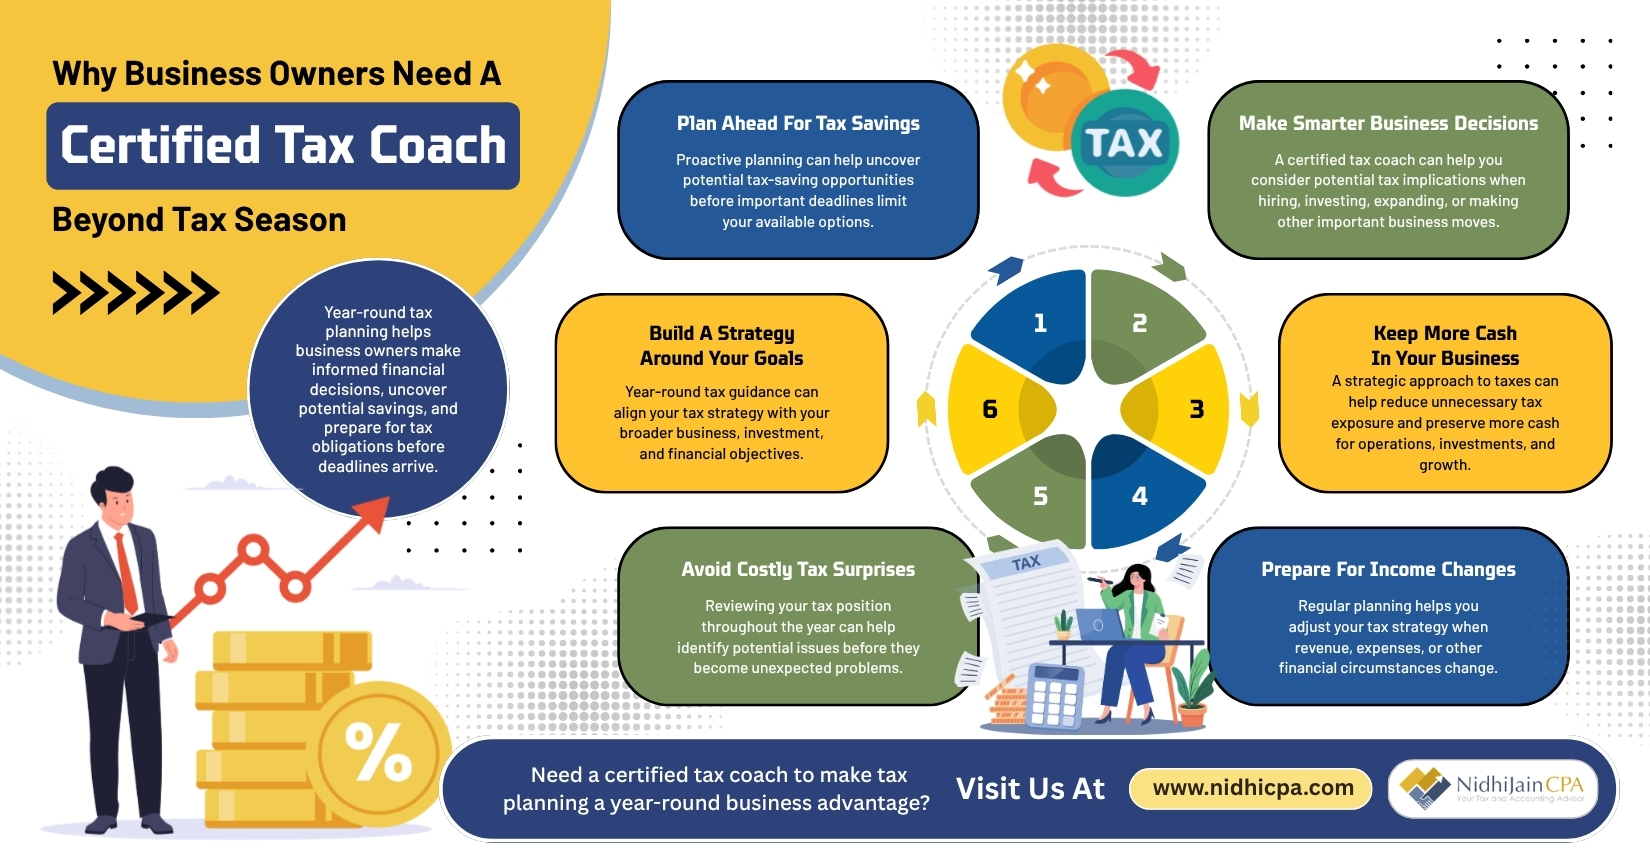
Strategic tax planning can help identify all applicable credits and deductions for maximum savings.
Startup Tax Management Tips
Follow these best practices to stay tax-compliant:
- Keep detailed records of all income and expenses. Hiring a bookkeeper can simplify this process.
- Invest in accounting software to organize payroll, receipts, and invoices.
- File your taxes early to avoid penalties or delays.
- Consult a tax accountant to file accurate returns and receive expert guidance.
Using business tax filing services can save time and reduce stress, allowing you to focus on growing your business.
Master Your Startup Taxes with Nidhi Jain CPA
Navigating taxes doesn’t have to be a challenge. The 2025 startup tax guide for entrepreneurs can make tax management straightforward.
Nidhi Jain CPA provides personalized support for bookkeeping and business tax filing in the Bay Area, helping you stay on top of your finances. With our expertise in tax planning in the Bay Area, you can focus on growing your business while we manage the details.
Contact us today to simplify your startup’s tax process and set your business up for long-term success!