
Maintaining regular financial statements is a fundamental practice for both businesses and individuals. It is essential for effective bookkeeping and accounting, ensuring financial health, and making informed decisions. Let’s explore why maintaining regular financial statements is crucial.
Clarity in Financial Health
Regular financial statements provide a clear picture of financial health. They include critical documents such as balance sheets, income statements, and cash flow statements. These records allow you to track your income, expenses, and profits systematically. Without these, it’s challenging to understand your financial position and make necessary adjustments.
Effective Bookkeeping and Accounting
Bookkeeping and accounting are the backbone of financial management. Regular financial statements ensure that all financial transactions are recorded accurately and systematically. This not only helps in keeping track of day-to-day financial activities but also in maintaining transparency. Proper bookkeeping allows for efficient management of resources, minimizes errors, and ensures compliance with financial regulations.
Facilitating Tax Preparation
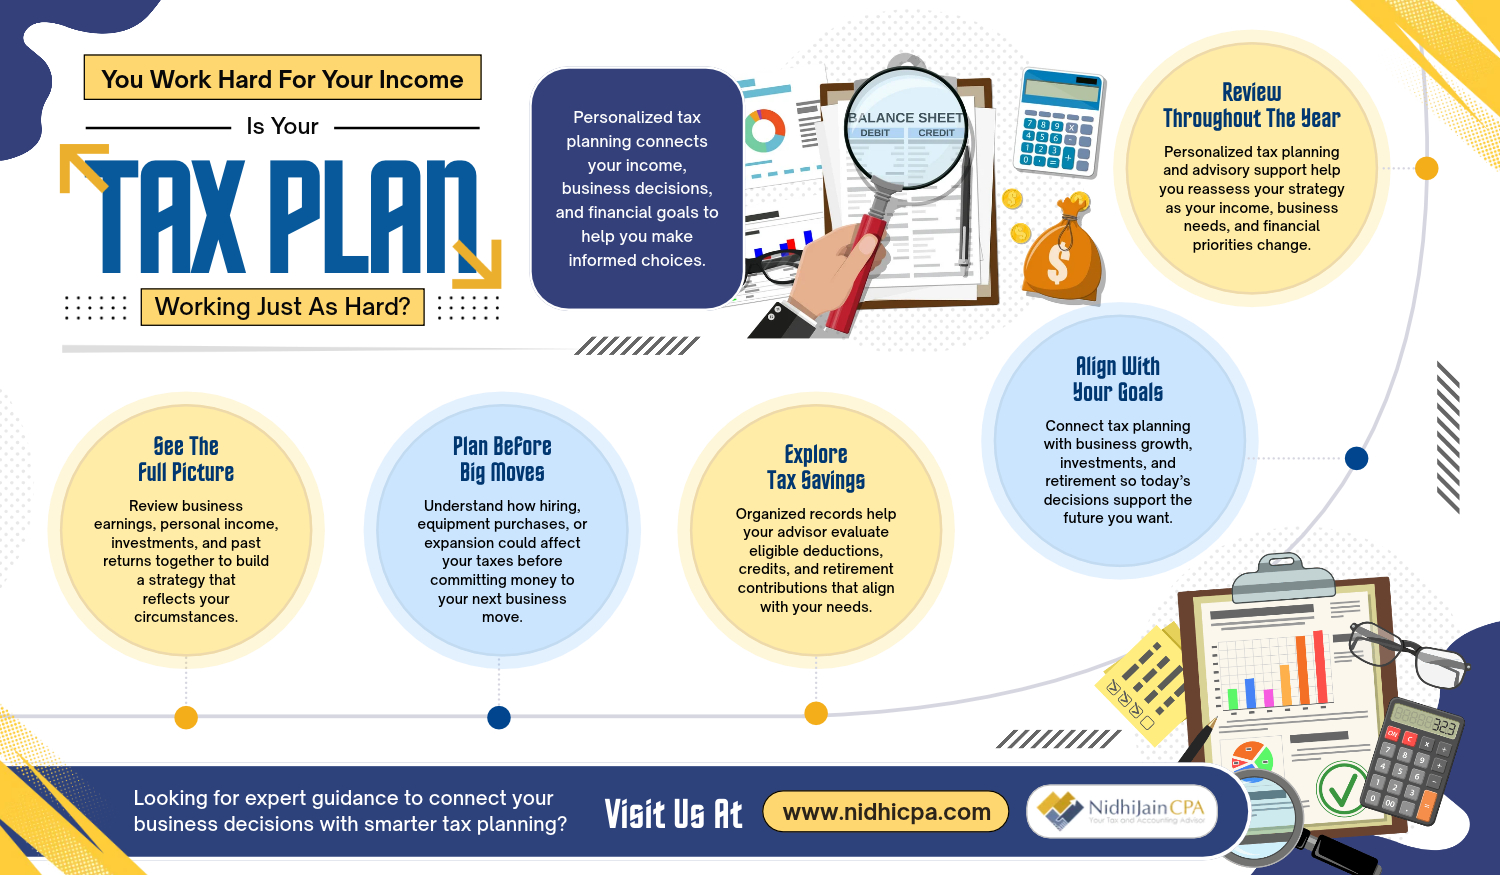
One of the most significant benefits of maintaining regular financial statements is the ease of tax preparation. When your financial records are up-to-date, it becomes simpler for your tax advisor or personal accountant to prepare and file taxes accurately. This not only saves time and reduces stress but also minimizes the risk of errors and penalties. It ensures you are taking advantage of all possible deductions and credits, ultimately leading to potential tax savings.
Building Credibility with Stakeholders
Regular financial statements enhance credibility with stakeholders such as investors, creditors, and regulatory bodies. Investors are more likely to invest in businesses that demonstrate financial stability and transparency. Creditors, too, prefer lending to entities that maintain consistent financial records. Transparent financial statements build trust and confidence, which is vital for long-term relationships and growth.
Planning and Forecasting
Maintaining regular financial statements aids in effective planning and forecasting. By analyzing past financial data, you can identify trends, set realistic budgets, and forecast future performance. This proactive approach helps in anticipating potential challenges and seizing opportunities, ensuring sustainable growth and financial stability.
Compliance and Legal Requirements
Regular financial statements ensure compliance with legal and regulatory requirements. Different jurisdictions have varying requirements for financial reporting, and failing to comply can result in severe penalties. Maintaining accurate and regular financial statements ensures that you meet all necessary legal obligations and avoid any legal repercussions.
If you’re in the Bay Area and looking to streamline your bookkeeping and accounting processes, Nidhi Jain CPA is here to help. With expertise in maintaining regular financial statements, Nidhi Jain ensures that your financial records are accurate, up-to-date, and compliant with all regulations. Visit our website or call us now to schedule a consultation and take the first step towards achieving your financial goals.