
Taxes can be a significant expense for businesses that can eat away at their profits. However, with proper planning and strategizing, businesses can reduce their tax liabilities and save money. This blog will explore some effective strategies businesses can use to save taxes while understanding the importance of comprehending their tax liabilities.
Understanding Your Taxes
Before we delve into the strategies, it is essential to understand the basics of taxes. Every business has to pay taxes, and the amount of tax a business pays depends on various factors, such as the type of business, its income, and its expenses. It is crucial for business owners to have a clear understanding of their tax liabilities to avoid overpaying or underpaying taxes.
One effective strategy to understand your taxes is to seek professional help from a tax expert or accountant. These professionals can provide insights into the tax laws and regulations, help you identify tax credits and deductions, and ensure you comply with tax laws to avoid penalties.
Strategies to Help Businesses Save Taxes
1. Keep Accurate Records
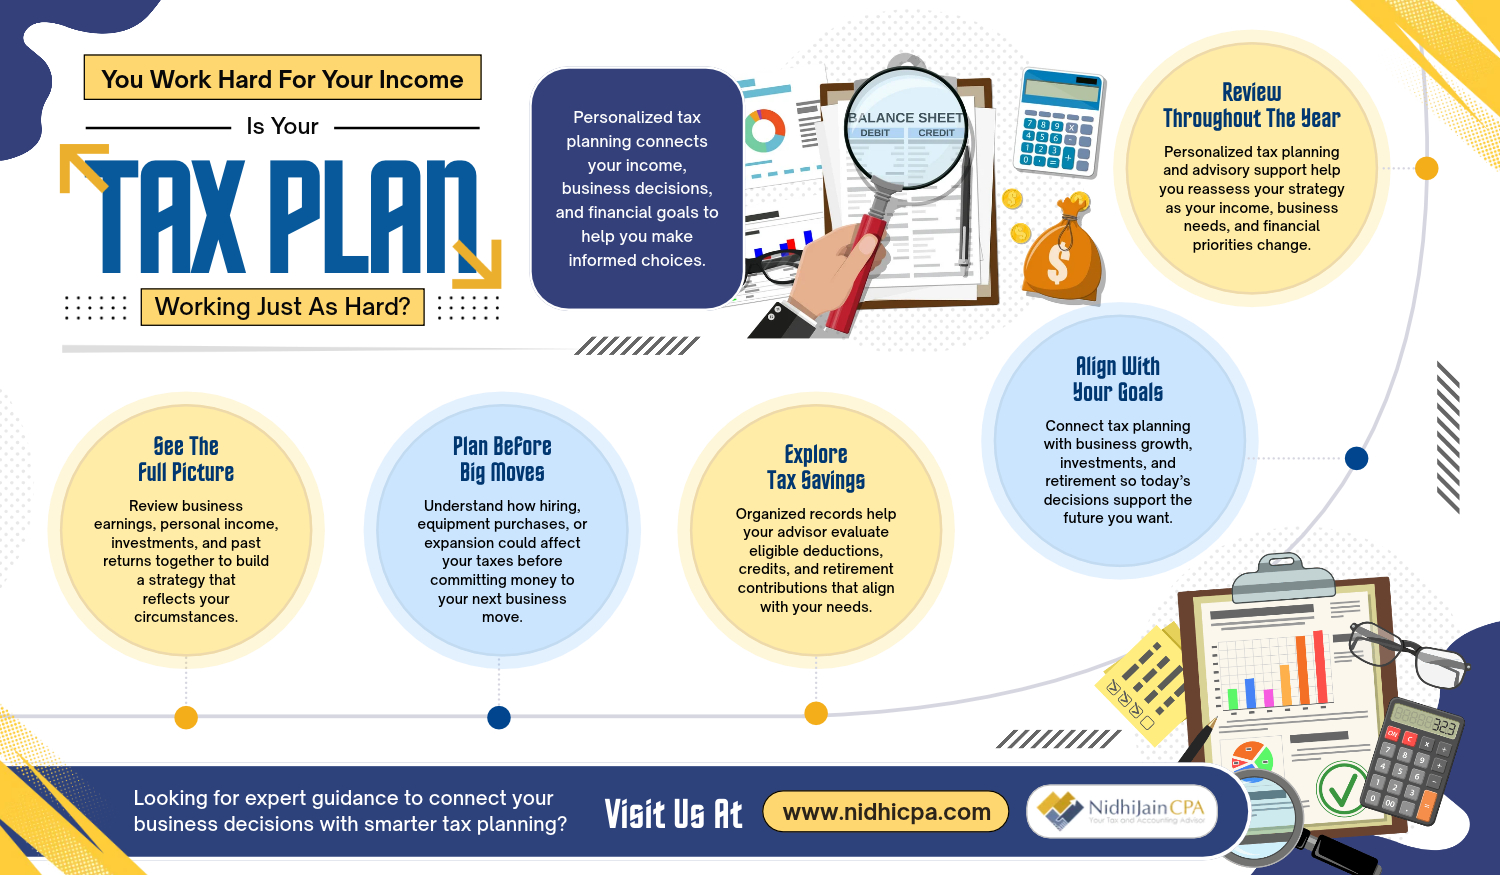
Maintaining accurate financial records is crucial for businesses, as it enables them to track their income and expenses. Organized records can help businesses identify their deductible expenses and maximize tax deductions. Accurate records can also help businesses avoid mistakes and penalties that may arise from non-compliance.
2. Take Advantage of Deductions
Deductions are a crucial aspect of reducing tax liabilities for businesses. Deductible expenses are necessary for running the business and are not considered personal expenses. Examples of deductible expenses include employee salaries, rent, and utilities. Businesses can significantly reduce their taxable income by identifying and taking advantage of these deductions.
3. Use Retirement Plans
Retirement plans such as 401(k)s and IRAs can effectively reduce tax liabilities for businesses. These plans allow businesses to make tax-deductible contributions to their employees’ retirement accounts. Not only does this reduce the business’s taxable income, but it also helps attract and retain talented employees.
4. Consider Depreciation
Depreciation is a tax deduction allowing businesses to deduct their assets’ costs over time. By considering depreciation, businesses can reduce their taxable income and save on taxes. It is important to note that depreciation rules can be complex, and businesses should consult a tax professional before making any decisions.
5. Plan Your Business Structure
Choosing the right business structure can have a significant impact on your taxes. For example, a sole proprietorship is taxed differently than a corporation. It is important to consult with a tax professional to determine the best business structure for your business.
To Sum Up
At NidhiJain CPA, every client deserves personalized attention and exceptional service. We are committed to assisting our clients in achieving their financial goals and work tirelessly to provide the guidance they need to succeed.
So if you’re looking for an expert to assist your business with tax saving strategies and business tax services bay area, look no further than NidhiJain CPA. Contact us to learn more about our tax-saving strategies for businesses and how we can help your business achieve its financial goals.