
Common Tax Mistakes That Could Cost You Money

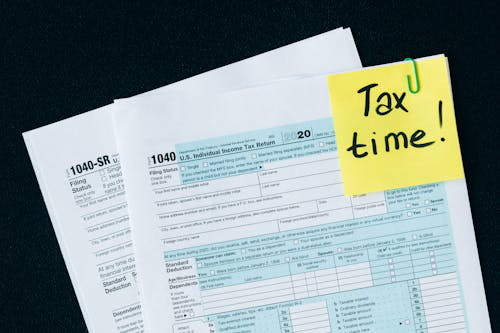
A stack of tax documents, forms, and receipts organized for accurate filing.

Tax season can be stressful, and errors in your return can lead to costly penalties or missed deductions. Whether you’re managing business tax filing or handling your personal taxes, certain common mistakes could impact your finances. By understanding these pitfalls, you can take steps to ensure a smoother filing process and maximize your savings.

Incorrect Income Reporting:

One of the most frequent tax filing mistakes is failing to report all sources of income. Many individuals forget about freelance work, side gigs, or investment earnings that must be declared. This oversight can trigger IRS audits and penalties. Keeping accurate financial records with the help of bookkeeping and accounting services can help prevent errors and ensure all taxable income is accounted for.

Overlooking Deductions and Credits:

Tax deductions and credits can significantly reduce your tax burden, but many people fail to claim them due to a lack of awareness. From education expenses to home office deductions, missing out on these benefits can cost you. Consulting a certified tax planner in San Francisco ensures that you take full advantage of every available deduction while staying compliant with tax laws.

Filing Late or Missing Deadlines:

Procrastinating on your taxes can lead to late penalties and interest charges. If you’re handling complex business tax filing, staying organized throughout the year is essential. A tax consultant can help you track important deadlines and avoid unnecessary fees that come with late submissions.

Mistakes in Filing Status and Dependents:

Choosing the wrong filing status or incorrectly listing dependents can affect your tax liability. Many taxpayers overlook status options that could offer better tax advantages. Working with a personal tax accountant in San Francisco can help determine the most beneficial filing status based on your financial situation.

Incorrectly Calculating Tax Liability:

Errors in tax calculations, whether underpaying or overpaying, can create financial strain. An experienced tax advisor can help you accurately assess your tax obligations, ensuring you neither owe unexpected amounts nor miss out on potential refunds.

Ignoring State and Local Tax Requirements:

Many taxpayers focus on federal taxes but forget about state and local tax obligations. This can lead to unexpected tax bills. A personal accountant can guide you through multi-jurisdictional tax rules to prevent any surprises.
A couple reviewing tax documents with a professional accountant offering assistance. 

Stay Informed to Avoid Costly Mistakes:

Avoiding tax filing mistakes requires careful planning and attention to detail. Staying proactive with your financial records and seeking professional guidance from Nidhi Jain CPA can help you navigate the complexities of tax season efficiently.

Want to stay ahead of tax season? Dive into the Nidhi Jain CPA blogs for expert insights and smart strategies to keep your finances on track!

Related Blogs

This photo shows some tax documents.

Receiving an IRS notice showing a tax balance can be stressful, particularly when paying the full amount is not financially realistic. Ignoring the balance, however, does not make the liability disappear. Interest and applicable penalties can continue to accrue until the amount is paid.

This guide explains what taxpayers should organize before requesting an arrangement, what payment options may be available, and how IRS payment plan help can make the process easier to navigate.

Start by Understanding What You Owe

Before requesting a payment arrangement, review your IRS notices and determine the tax year, outstanding balance, penalties, and interest involved. Your IRS Online Account can provide information about your current balance and payment history.

If you have unfiled returns, address those obligations as well. Generally, taxpayers must be current with required filings before certain payment plans can be considered.

Prepare the Information the IRS May Need

Having your financial information organized before applying can make the process more manageable.

Gather Your Tax Records

Keep copies of relevant tax returns, IRS notices, previous payment records, and correspondence together. This gives you a clearer picture of the liability you are trying to resolve.

This photo shows some tax documents.

Review Your Income

Collect recent information showing wages, self-employment income, investment income, or other sources of money you receive. Accurate income information can be important when determining what payment arrangement may be appropriate.

Document Your Regular Expenses

Review housing, utilities, transportation, insurance, food, medical expenses, debt payments, and other recurring costs. Some situations may require additional financial information or collection forms.

Do Not Wait Until Collection Problems Escalate

Addressing an unpaid balance promptly gives you more opportunity to understand available options. If you cannot pay everything immediately, paying what you can and exploring an arrangement may be preferable to simply ignoring the liability.

Professional tax resolution services can also help taxpayers review their circumstances and understand potential approaches for addressing outstanding liabilities.

Get Help Addressing an Outstanding Tax Balance

Tax debt can involve more than simply choosing a monthly payment amount. Nidhi Jain CPA provides back tax solution support, tax planning, and accounting guidance to help taxpayers understand their obligations and work toward addressing outstanding balances.

If you need a tax advisor in the Bay Area for an unresolved tax matter, contact Nidhi Jain CPA to discuss your situation.




