
Many business owners fear underpaying their taxes and facing penalties. But what if you’re actually overpaying? While it may seem safer to overestimate, consistently paying more than necessary drains your working capital and limits how you can invest in your business. Accurate San Jose tax planning helps you strike the right balance, staying compliant without sacrificing cash flow.
Sign #1: Your Quarterly Payments Rarely Match Your Final Tax Bill
If your estimated payments end up being significantly higher than your actual tax due, you’re essentially giving the IRS an interest-free loan. While this might protect you from penalties, it also ties up money that could be used for growth, hiring, or debt reduction. A tax accountant can help recalibrate your estimates based on real-time income and expenses.
Sign #2: You’re Using Last Year’s Income as Your Only Forecast
Many small businesses base estimated taxes on the previous year’s income. While this is common, it can be inaccurate, especially if your revenue fluctuates. Seasonal businesses or those experiencing growth may find that past data doesn’t reflect current performance. Tax planning services use up-to-date records to create a more accurate forecast for each quarter.
Sign #3: Your Books Aren’t Up to Date
Reliable estimates depend on clean, current books. If you’re behind on categorizing expenses or reconciling accounts, your estimates are likely off. Partnering with a bookkeeping expert ensures your financials are always ready for accurate tax projections and smarter decisions.
Sign #4: You Don’t Account for Major Deductions Until Year-End
Some business owners wait until tax time to total up deductions, missing opportunities to lower their quarterly payments. Expense categories like equipment purchases, home office costs, or vehicle use should be tracked consistently. A tax planning consultant ensures deductions are considered early and often, reducing unnecessary overpayments throughout the year.
Sign #5: You Haven’t Revisited Your Payment Strategy
Tax law changes, income swings, or new business expenses all affect your tax liability. If you haven’t adjusted your estimated tax plan in the last 6–12 months, it’s time for a review. A professional CPA in San Jose can help tailor a payment schedule that reflects your current situation, not last year’s.
Don’t Let Overpayments Hold Back Your Business
Paying too much in estimated taxes may seem like the “safe” route, but it actually limits your financial agility. With accurate tax planning in San Jose, you can stay compliant while keeping more cash in your business throughout the year.
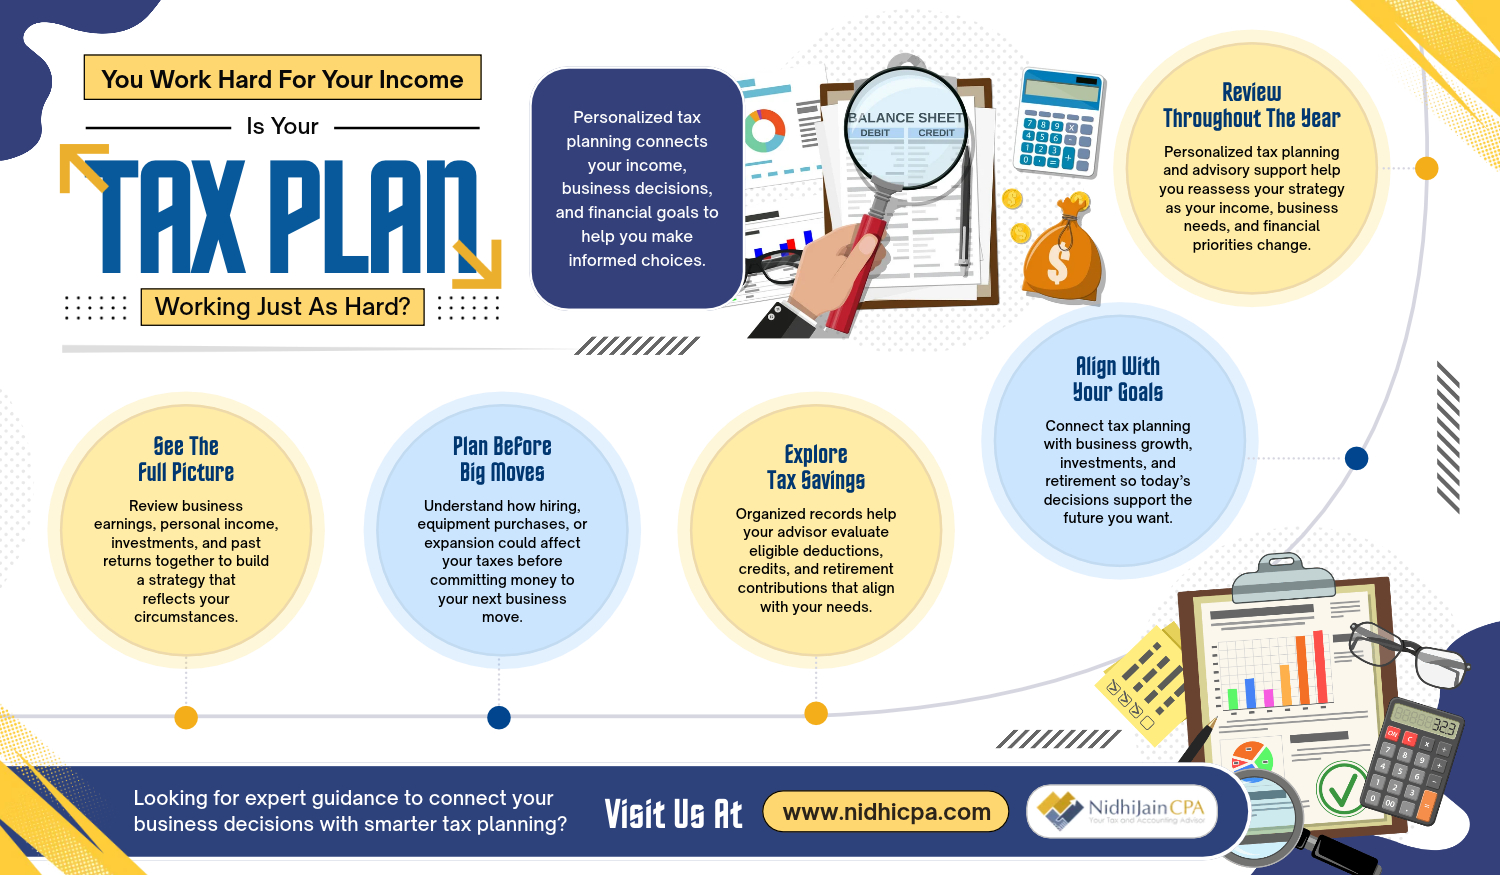
Nidhi Jain CPA helps business owners across the Bay Area find the ideal tax strategy through real-time forecasting, accurate bookkeeping, and personalized support. Whether you’re an independent contractor, LLC, or S-Corp, we’ll help you avoid overpayments and unlock better cash flow.
Need help reviewing your estimated tax payments? Explore our blog for practical tax tips, or contact us to schedule a tax planning review.