
Starting a business comes with tough decisions, especially when choosing the right entity. Many business owners in the Bay Area rush into incorporation without fully understanding how it impacts taxes, compliance, and long-term goals. Working with a CPA Bay Area expert early on can prevent common mistakes that slow down growth and increase tax burdens. Here’s a closer look at what goes wrong and what to do instead.
Choosing the Wrong Entity Type
Many new business owners file as an LLC or sole proprietorship without considering long-term tax implications. While LLCs are flexible and popular, they may not always offer the best tax advantages, especially for businesses expecting to grow quickly. Filing as an S-Corp can reduce self-employment taxes, but it comes with stricter compliance and payroll requirements. Selecting the wrong structure often leads to costly amendments or restructures down the line. It’s important to assess profit projections and growth plans before choosing an entity.
Overlooking State-Specific Requirements
California has its own franchise tax rules, reporting deadlines, and fee structures. New businesses often miss filing the initial Statement of Information, resulting in penalties. Others underestimate the $800 annual minimum franchise tax or forget to account for estimated quarterly payments. Setting reminders and maintaining a compliance calendar can help avoid missing key obligations. Business owners also need to understand that California doesn’t recognize S-Corps the same way the IRS does, which may affect state tax filings differently.
Mixing Personal and Business Finances
Failing to separate personal and business finances is a frequent issue with new owners. Using personal bank accounts for business income and expenses not only complicates bookkeeping but also risks piercing the corporate veil, putting personal assets at risk. Opening a dedicated business bank account, applying for a business credit card, and using accounting software from day one can make a major difference in financial clarity and tax preparation.
Inconsistent or Incomplete Bookkeeping
Many entrepreneurs don’t prioritize bookkeeping during the startup phase, thinking they can catch up later. However, missing receipts, inconsistent categorization, and late entries lead to tax filing errors and missed deductions. Poor recordkeeping also makes it harder to prepare financial statements. Business owners should implement strong bookkeeping practices early on and review them quarterly to stay on track.
Waiting Too Long to Hire a Tax Consultant
Some business owners wait until tax season to speak with a professional. By then, it may be too late to take advantage of deductions, entity elections, or tax planning strategies that should have been implemented months earlier. Regular meetings with a qualified tax consultant can provide guidance on estimated payments, credits, and potential risks based on current activity.
What to Do Instead and Where to Learn More
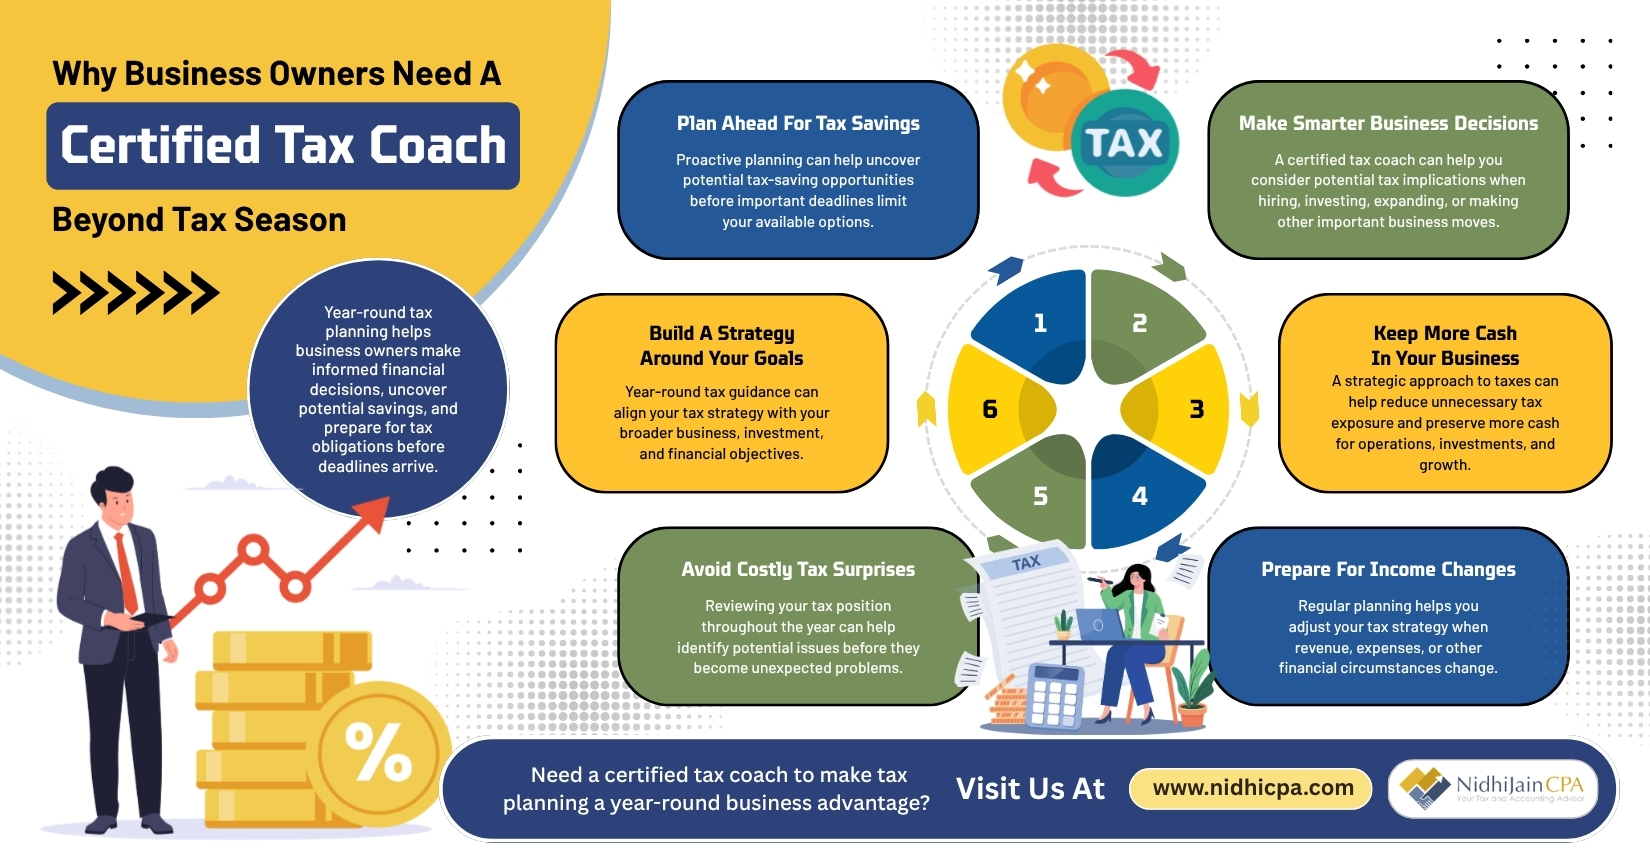
The best way to avoid early entity mistakes is to get informed and plan ahead. Partnering with a knowledgeable CPA Bay Area expert can make it easier to choose the right entity, improve bookkeeping practices, and stay on top of quarterly financial reviews. For more insights on tax planning, compliance tips, and smart startup practices, read the blog from Nidhi Jain CPA.