The Guide for Handling Taxes as New Homeowners

a man using a laptop on a table

Are you considering buying your first home and are confused about how to handle taxes as a first-time homeowner?

Tax laws vary significantly state by state. Thus, handling taxes as a new homeowner can be overwhelming, especially since you’re setting up all kinds of new systems.

While some people know everything about this subject, others can be clueless about it.


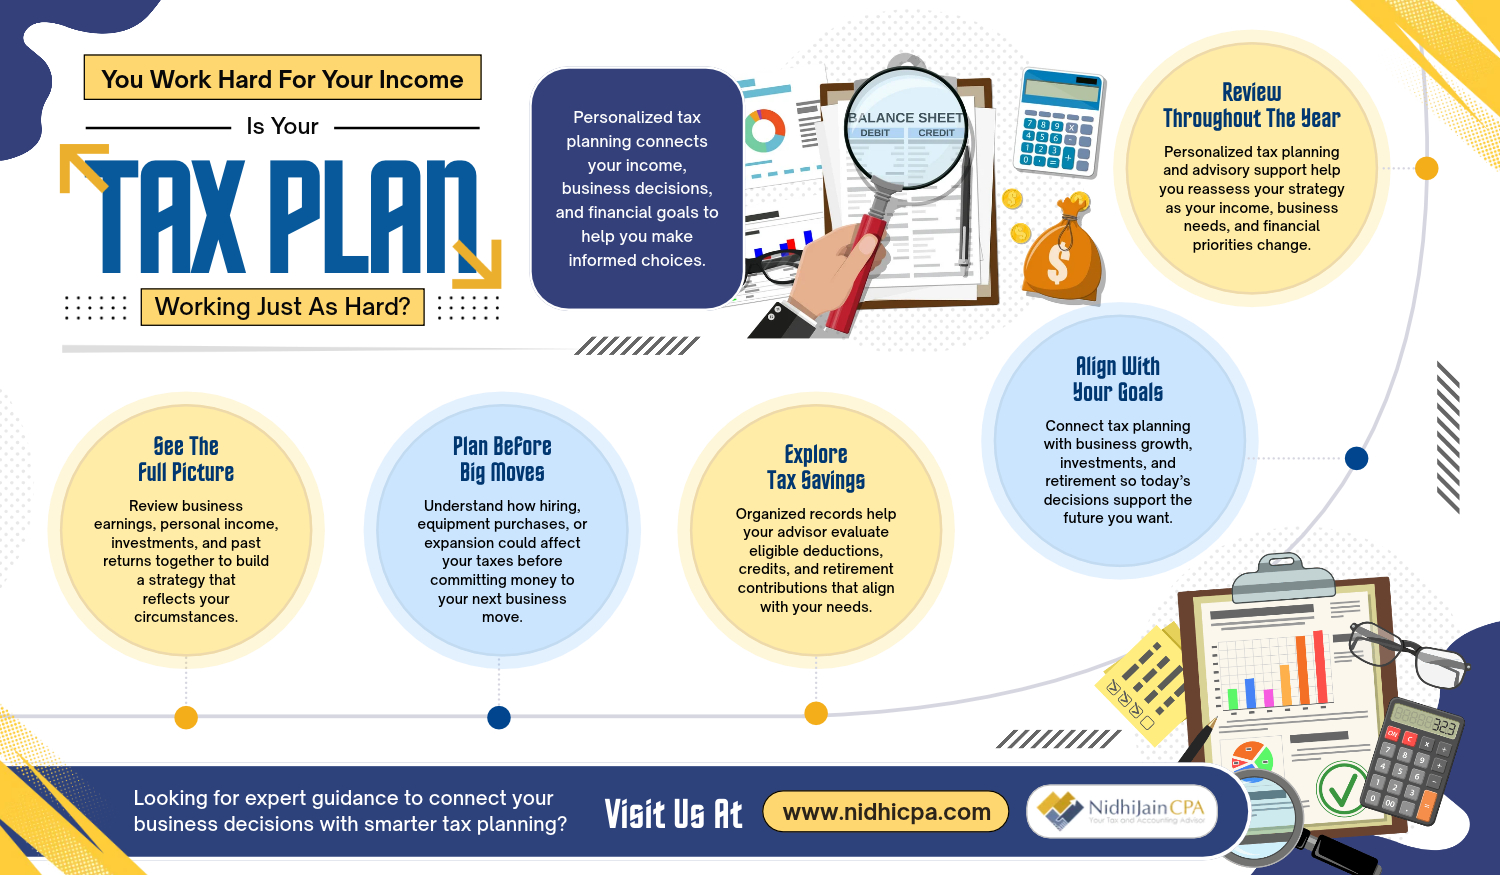
Experts recommend hiring a tax filing service to ensure that your tax reports are accurate and error-free. Nidhi Jain CPA offers reliable and affordable tax filing services to individuals and businesses in California.


This guide can help out first-time new homeowners with their taxes. Take a look:

1. Do Your Homework When You Buy a Home

Before you buy, make sure you understand the home’s current tax situation. If you’re buying from an estate or trust, consult a tax expert and ensure there are no liens or outstanding taxes before making an offer.


2. Understand Your Tax Bracket

The tax bracket is the range of income you fall into for federal, state, and local taxes. It’s important to understand your tax bracket so you can make sure you’re paying the right amount of tax and not overpaying.


Your tax bracket is calculated by the IRS based on your filing status, personal exemption amount, and taxable income, among other things.


The following tax brackets apply to homeowners:

  • The first $20,000 of your gross annual income is taxed at 10 percent.
  • The next $30,000 of your gross annual income is taxed at 15 percent.
  • The remaining amount of your gross annual income over $25,000 is taxed at 25 percent.

3. Understand the Constitution

Make sure you understand what constitutes a rental property and what it means for your taxes. To qualify as a rental property, you must have an agreement with someone else who will occupy the property and make improvements to it. If you don’t have that agreement, then all of the income from the property will be yours.
a man using a laptop

4. Maintain All Records

Keep good records of all expenses related to running your rental property (such as utilities). You may also want to consult an accountant who specializes in small businesses so that they can help identify specific deductions that could be available in addition to any standard deductions


If you’re looking for a professional tax preparation service as homeowner in San Francisco Bay Area, Nidhi Jain CPA has got you covered. We provide innovative tax planning and individual tax filing services. Our highly qualified and experienced certified public accountants in USA also offer back tax solutions, bookkeeping, and payroll services.


Call us today to learn more about our professional accounting services.
 

Related Blogs

This photo shows some tax documents.

Receiving an IRS notice showing a tax balance can be stressful, particularly when paying the full amount is not financially realistic. Ignoring the balance, however, does not make the liability disappear. Interest and applicable penalties can continue to accrue until the amount is paid.

This guide explains what taxpayers should organize before requesting an arrangement, what payment options may be available, and how IRS payment plan help can make the process easier to navigate.

Start by Understanding What You Owe

Before requesting a payment arrangement, review your IRS notices and determine the tax year, outstanding balance, penalties, and interest involved. Your IRS Online Account can provide information about your current balance and payment history.

If you have unfiled returns, address those obligations as well. Generally, taxpayers must be current with required filings before certain payment plans can be considered.

Prepare the Information the IRS May Need

Having your financial information organized before applying can make the process more manageable.

Gather Your Tax Records

Keep copies of relevant tax returns, IRS notices, previous payment records, and correspondence together. This gives you a clearer picture of the liability you are trying to resolve.

This photo shows some tax documents.

Review Your Income

Collect recent information showing wages, self-employment income, investment income, or other sources of money you receive. Accurate income information can be important when determining what payment arrangement may be appropriate.

Document Your Regular Expenses

Review housing, utilities, transportation, insurance, food, medical expenses, debt payments, and other recurring costs. Some situations may require additional financial information or collection forms.

Do Not Wait Until Collection Problems Escalate

Addressing an unpaid balance promptly gives you more opportunity to understand available options. If you cannot pay everything immediately, paying what you can and exploring an arrangement may be preferable to simply ignoring the liability.

Professional tax resolution services can also help taxpayers review their circumstances and understand potential approaches for addressing outstanding liabilities.

Get Help Addressing an Outstanding Tax Balance

Tax debt can involve more than simply choosing a monthly payment amount. Nidhi Jain CPA provides back tax solution support, tax planning, and accounting guidance to help taxpayers understand their obligations and work toward addressing outstanding balances.

If you need a tax advisor in the Bay Area for an unresolved tax matter, contact Nidhi Jain CPA to discuss your situation.