
Real estate investment offers excellent opportunities for financial growth, but taxes can eat into your profits if you’re not careful. This guide provides real estate tax tips to help you maximize deductions, minimize liabilities, and retain more of your hard-earned income.
Understand Depreciation
Depreciation is a powerful tax-saving tool for real estate investors. It allows you to deduct the wear and tear on your property over time.
- What You Can Depreciate: Residential rental properties can be depreciated over 27.5 years, and commercial properties over 39 years.
- Benefits: Depreciation reduces taxable income without impacting your cash flow.
- Pro Tip: Remember that land cannot be depreciated, so accurately allocate purchase costs between land and building.
Manage Capital Gains
When you sell a property for more than its purchase price, you’re subject to capital gains tax. Proper planning can reduce your tax burden.
- Long-Term vs. Short-Term Gains: Properties held for more than a year are taxed at lower long-term rates.
- 1031 Exchanges: Use this strategy to defer taxes by reinvesting proceeds into another property.
- Adjust Basis: Track expenses like renovation costs, as they increase your cost basis and reduce taxable gains.
Leverage Tax Deductions
Tax deductions lower your taxable income. Here are some common deductions real estate investors can claim:
- Mortgage Interest: Deduct interest paid on loans for investment properties.
- Property Taxes: Local and state property taxes are deductible.
- Repairs and Maintenance: Immediate expenses like fixing a roof or replacing a water heater qualify.
- Business Expenses: Office supplies, software, and marketing costs also count.
Use Tax-Advantaged Accounts
Certain accounts can help reduce your taxable income further:
- Self-Directed IRAs: Invest in real estate through a retirement account for tax-deferred or tax-free growth.
- Health Savings Accounts (HSAs): For qualifying individuals, HSAs can be used to save tax-free funds for medical expenses.
Track and Organize Expenses
Keeping meticulous records of all expenses is important to maximize deductions and minimize tax liabilities. Here’s how to stay organized:
- Document All Expenses: Record every expense related to your properties, including repairs, utilities, insurance, and property management fees.
- Track Travel Expenses: If you travel for property management or related business, document transportation, lodging, and meal costs.
- Use Accounting Software: Consider using accounting tools or software to automate the tracking process and maintain accurate records.
Work With a Tax Advisor
Tax laws are complex, and real estate investors can benefit significantly from professional advice.
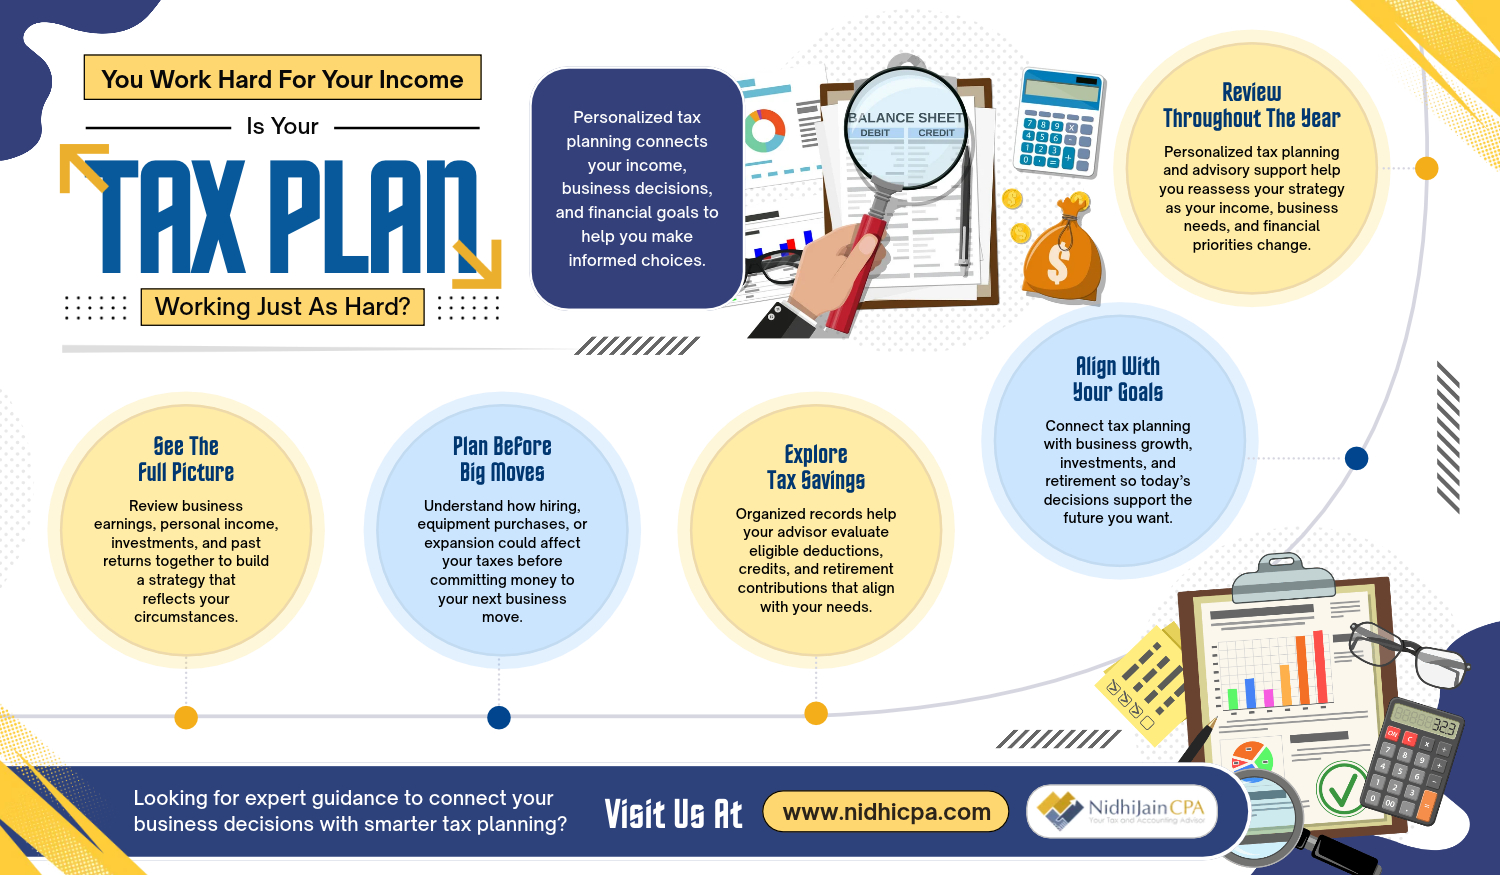
- Tax Planning: A qualified professional ensures you’re using all available strategies to save money.
- International Investors :Seek an international tax accountant if you’re investing across borders.
Maximize Savings With Nidhi Jain CPA
Understanding real estate taxes is essential to maximizing your profits. Whether it’s depreciation, capital gains management, or strategic deductions, these real estate tax tips will keep you ahead.
To ensure you fully optimize your tax opportunities, partnering with an experienced tax advisor in the Bay Area can make all the difference. Nidhi Jain CPA offers expert guidance for real estate investors, providing services such as bookkeeping, accounting, and tax planning in the Bay Area, San Francisco, and San Jose.
Take control of your real estate tax strategy today. Contact us to schedule a consultation!