How Rising Operating Costs Should Influence Your Tax Planning Strategy

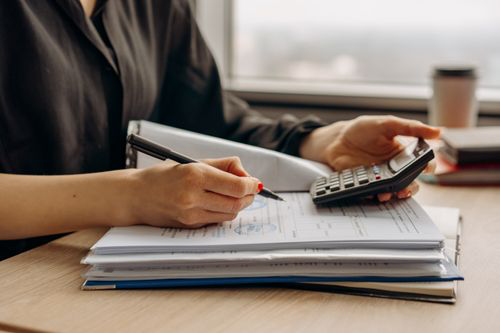
Business professional calculating operating costs while reviewing financial documents

Higher operating costs do more than reduce profit. They can also make last quarter’s tax estimate outdated. In the Los Angeles area, consumer prices were 3.3% higher in June 2026 than one year earlier. Energy prices rose 15.1% during the same period, according to the U.S. Bureau of Labor Statistics.

Higher fuel, insurance, rent, inventory, and borrowing costs now compete for the cash needed for taxes. This is where corporate tax planning becomes important. Waiting until filing season may leave little time to correct payments, document expenses, or plan purchases.

Update Tax Projections as Costs Change

Do not rely on a tax estimate prepared at the start of the year. Review revenue, gross margin, financing costs, and operating expenses every quarter.

If profit falls, estimated payments may need adjustment. If revenue rises faster than expenses, the company may need to reserve more cash. Regular tax planning can reduce underpayment risk and avoid unnecessary overpayments.

Record Deductible Expenses Correctly

The IRS generally allows deductions for ordinary and necessary business expenses. However, the timing and treatment of each cost can differ.

Rent, utilities, insurance, software, professional fees, and advertising may be currently deductible. Major improvements, equipment, and certain startup costs may need to be capitalized or deducted over time.
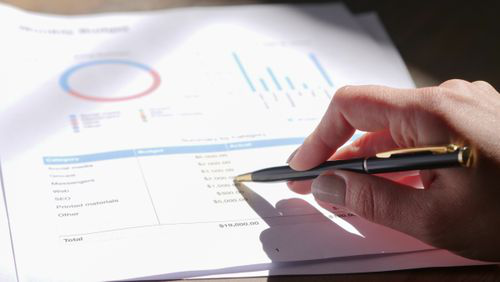
Hand holding a pen over a printed business expense report with financial charts

Keep records showing the amount, date, vendor, and business purpose. A tax planning consultant can help separate repairs from improvements and business costs from personal spending.

Review the Tax Cost of Financing

Higher interest rates increase the cost of loans for equipment, inventory, and expansion. Business interest is often deductible, but Section 163(j) may limit the amount some taxpayers can claim in the current year. Disallowed interest may need to be carried forward.

Before taking on debt, compare the after-tax interest cost with expected cash flow. Corporate tax planning should account for deduction limits, loan terms, and future payment pressure.

Time Equipment Purchases With Care

A tax deduction should not be the only reason to buy an asset. Confirm that the purchase supports operations and fits the budget. Then review the placed-in-service date, Section 179 eligibility, first-year depreciation, and future deduction needs.

Tax planning services can compare an immediate write-off with deductions spread across later years.

Control Rising Costs With Nidhi Jain CPA

Nidhi Jain CPA provides corporate tax planning for companies facing higher expenses and financing costs. Work with a tax planning consultant to review deductions, estimated payments, asset purchases, and cash needs before filing deadlines limit your options.

Contact our dedicated tax planning consultant from Nidhi Jain CPA.
Related Blogs

This photo shows some tax documents.

Receiving an IRS notice showing a tax balance can be stressful, particularly when paying the full amount is not financially realistic. Ignoring the balance, however, does not make the liability disappear. Interest and applicable penalties can continue to accrue until the amount is paid.

This guide explains what taxpayers should organize before requesting an arrangement, what payment options may be available, and how IRS payment plan help can make the process easier to navigate.

Start by Understanding What You Owe

Before requesting a payment arrangement, review your IRS notices and determine the tax year, outstanding balance, penalties, and interest involved. Your IRS Online Account can provide information about your current balance and payment history.

If you have unfiled returns, address those obligations as well. Generally, taxpayers must be current with required filings before certain payment plans can be considered.

Prepare the Information the IRS May Need

Having your financial information organized before applying can make the process more manageable.

Gather Your Tax Records

Keep copies of relevant tax returns, IRS notices, previous payment records, and correspondence together. This gives you a clearer picture of the liability you are trying to resolve.

This photo shows some tax documents.

Review Your Income

Collect recent information showing wages, self-employment income, investment income, or other sources of money you receive. Accurate income information can be important when determining what payment arrangement may be appropriate.

Document Your Regular Expenses

Review housing, utilities, transportation, insurance, food, medical expenses, debt payments, and other recurring costs. Some situations may require additional financial information or collection forms.

Do Not Wait Until Collection Problems Escalate

Addressing an unpaid balance promptly gives you more opportunity to understand available options. If you cannot pay everything immediately, paying what you can and exploring an arrangement may be preferable to simply ignoring the liability.

Professional tax resolution services can also help taxpayers review their circumstances and understand potential approaches for addressing outstanding liabilities.

Get Help Addressing an Outstanding Tax Balance

Tax debt can involve more than simply choosing a monthly payment amount. Nidhi Jain CPA provides back tax solution support, tax planning, and accounting guidance to help taxpayers understand their obligations and work toward addressing outstanding balances.

If you need a tax advisor in the Bay Area for an unresolved tax matter, contact Nidhi Jain CPA to discuss your situation.