
Inflation’s steady climb influences many aspects of financial planning, especially tax projections. As prices rise, tax thresholds and brackets are often adjusted for inflation, which directly impacts quarterly estimates and payments. Understanding how these adjustments work is essential for maintaining accurate tax planning services and avoiding penalties. This blog explores how rising inflation reshapes quarterly tax estimates, offers simple forecasting tweaks, and emphasizes the importance of proactive tax planning to ensure smooth tax compliance.
Inflation-Adjusted Tax Thresholds and Their Effect on Quarterly Payments
Inflation leads to increases in tax brackets and standard deductions, which can shift the way tax and accounting services are approached throughout the year. When thresholds are adjusted annually, taxpayers often find themselves in a different tax bracket than previous years, even if their income remains steady. For those who rely on quarterly estimates, these adjustments mean that payments need to be recalibrated to avoid overpaying or underpaying.
Simple Forecasting Tweaks to Stay Ahead of Inflation
To keep estimated taxes accurate amid rising inflation, it’s crucial to incorporate some simple forecasting adjustments. First, regularly review income projections with updated inflation rates in mind. For business owners, especially those engaged in business tax services, keeping an eye on inflation trends helps in adjusting income forecasts and expense estimations accordingly.
Additionally, consulting with a tax advisor or a personal tax accountant can provide valuable insights into how inflation impacts individual or business tax liabilities. Experienced accountants and international tax accountants in the Bay Area can assist in aligning estimates with the latest inflation data, ensuring optimal tax planning and compliance.
The Role of Accurate Tax Planning in a High-Inflation Environment
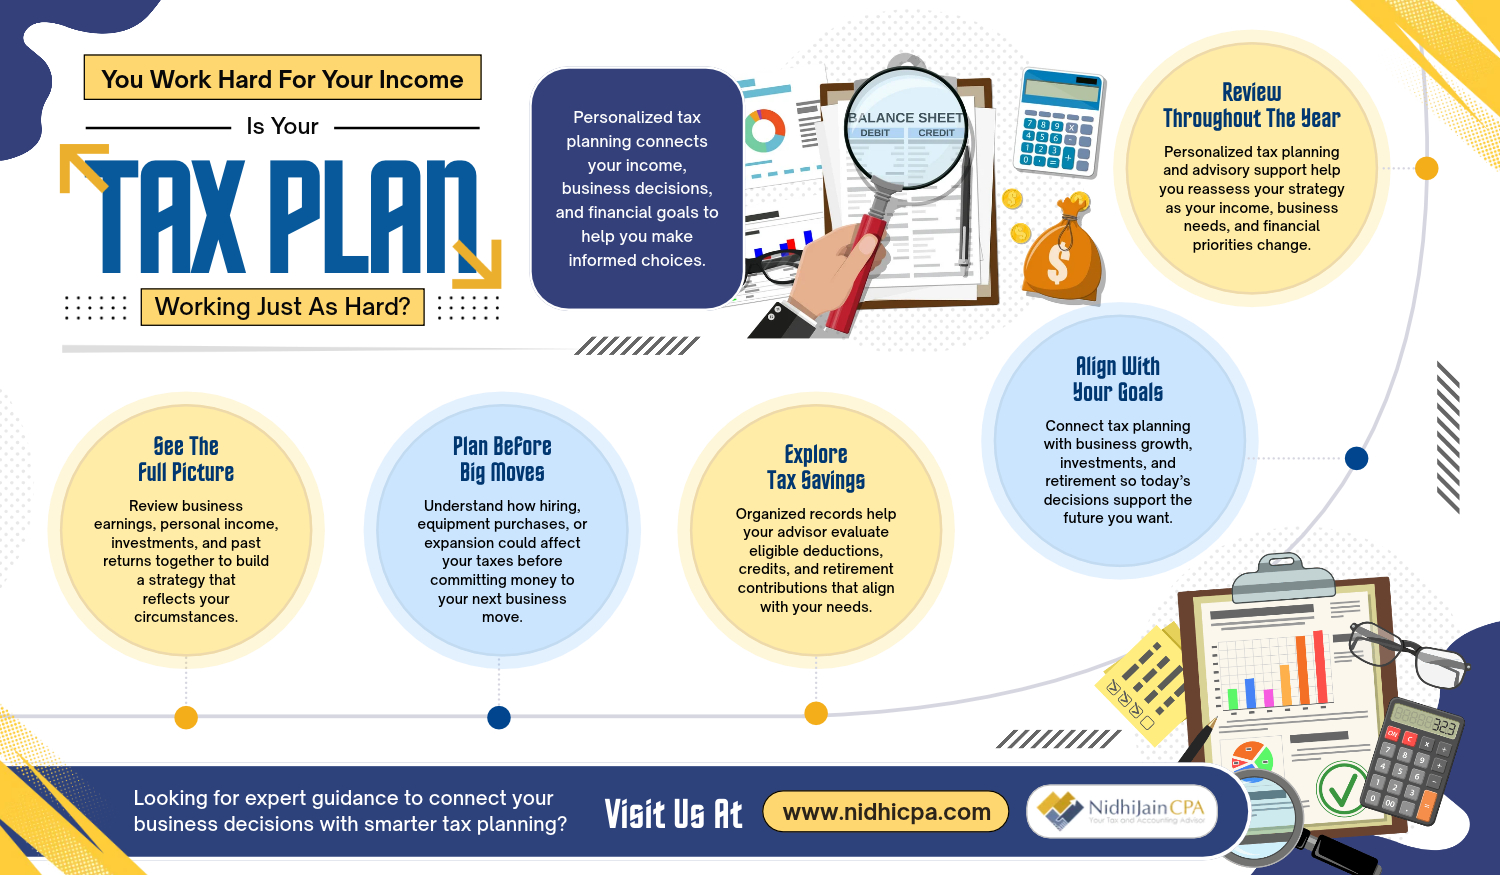
Effective tax planning services become even more vital during inflationary periods. Proper planning helps prevent surprises at tax time and ensures that estimated payments are aligned with real-time economic conditions. For businesses, this means adjusting profit forecasts, expense deductions, and tax credits based on inflation trends.
In the realm of tax resolution services and back tax solutions, staying ahead of inflation can prevent future liabilities by ensuring quarterly estimates are accurate. For those engaged in Bay Area bookkeeping and accounting, integrating inflation adjustments into financial records ensures consistent, compliant tax filings.
Staying Ahead of Inflation with the Right Tax Strategy
As inflation continues to influence the economy, it’s essential to incorporate inflation-aware strategies into overall tax planning services. Regularly updating income projections, adjusting quarterly estimates, and consulting with experienced tax advisors can help manage the impact of inflation effectively.
Businesses should emphasize flexible forecasts and maintain close communication with their personal accountant or international tax advisor to adapt to changing economic conditions. With the right approach, it’s possible to minimize penalties, optimize cash flow, and maintain compliance, even in a high-inflation environment.
Optimize Your Tax Strategy to Manage Inflation Effectively
Managing rising inflation requires proactive tax planning. At Nidhi Jain CPA, I am here to help you stay ahead. With my expertise as a trusted CPA in the Bay Area, I provide tailored tax planning services to reduce penalties, improve cash flow, and ensure compliance by adjusting quarterly estimates. My comprehensive tax resolution strategies help navigate inflation’s impact smoothly. Whether you need assistance with business tax services or personal tax filing, I customize solutions to fit your unique situation. Let’s work together to minimize surprises at tax time and maximize your savings. Contact me today to discuss how I can support your financial goals. Be sure to check out my blog for valuable tax tips and insights.