
Accurate financial information is the foundation of every successful business. However, financial records can quickly become unreliable when transactions are not regularly reviewed and verified. This is where annual and monthly reconciliation plays a critical role.
Reconciliation is the process of comparing financial records against bank statements, credit card statements, and other financial documents to ensure everything matches correctly. By performing regular reconciliations, businesses can identify errors, prevent discrepancies, and make better financial decisions based on accurate data.
What Is Annual and Monthly Reconciliation?
Reconciliation involves reviewing financial transactions and confirming that recorded amounts match actual financial activity.
This process typically includes:
- Comparing bank records to accounting records
- Identifying missing or duplicate transactions
- Verifying deposits and withdrawals
- Reviewing outstanding invoices and payments
- Correcting accounting errors
Both monthly and annual reconciliations help maintain consistency and accuracy throughout the year.
Why Monthly Reconciliation Matters
Monthly reconciliation allows businesses to detect issues before they become larger problems.
Benefits include:
- Improved financial accuracy
- Faster error detection
- Better cash flow visibility
- More reliable financial reports
- Reduced risk of fraud or unauthorized transactions
Businesses that perform regular reconciliations often have a clearer understanding of their financial position and can respond more quickly to potential issues.
Better Financial Reporting Leads to Better Decisions
When financial records are accurate, business owners can make decisions with greater confidence.
Reliable reporting supports:
- Budget planning
- Investment decisions
- Business expansion strategies
- Expense management
- Tax preparation
Many companies rely on Bay Area bookkeeping systems to maintain organized financial records, but reconciliation is what helps verify that those records are correct.
The Importance of Annual Reconciliation
While monthly reviews help maintain consistency, annual reconciliation provides a comprehensive review of financial activity before year-end reporting and tax preparation.
Annual reconciliation helps businesses:
- Confirm year-end balances
- Prepare accurate tax filings
- Identify unresolved discrepancies
- Improve audit readiness
- Strengthen overall financial controls
For companies preparing business tax filing requirements, accurate year-end records are especially important.
Reconciliation Supports Tax Compliance
Financial inaccuracies can create challenges during tax season. Missing transactions, incorrect balances, or duplicate entries may result in reporting errors that increase compliance risks.
Working with professionals who provide tax and accounting services can help ensure that reconciliation processes support accurate tax reporting and reduce the likelihood of costly mistakes.
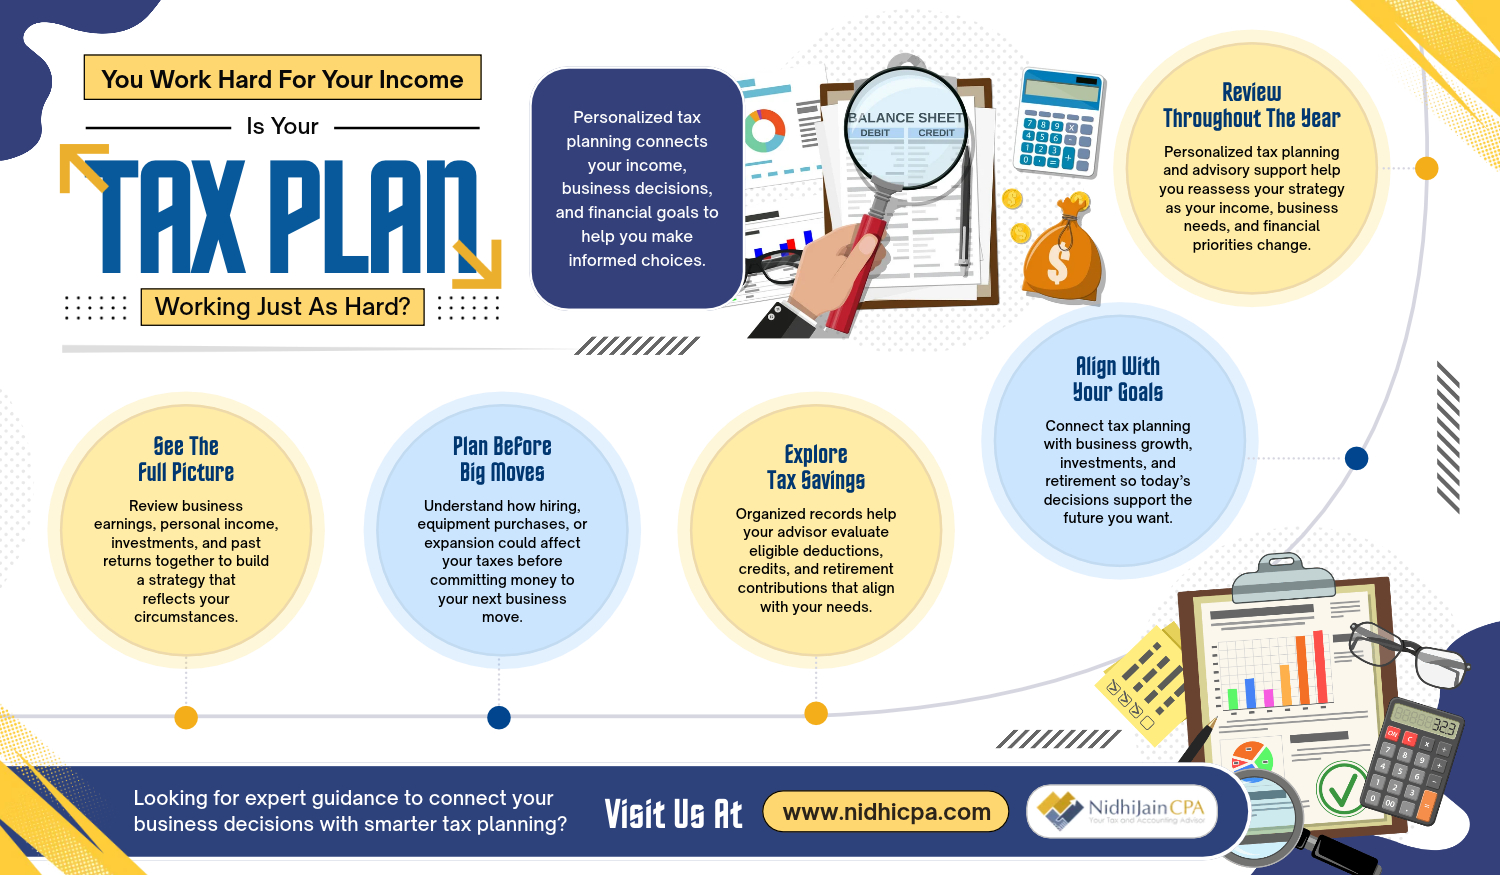
In addition, regular reviews provide valuable information that supports effective tax planning services throughout the year.
Build Stronger Financial Records with Professional Support
At Nidhi Jain CPA, we help businesses improve financial accuracy through structured bookkeeping, reconciliation, and reporting processes. Whether you need support with bookkeeping and accounting in Bay Area, year-end reviews, or ongoing financial management, we provide practical solutions designed to help businesses stay organized and informed.
Our goal is to help clients maintain accurate records, strengthen financial reporting, and make better business decisions through reliable accounting practices. Contact us today to learn how professional reconciliation support can benefit your business.