Financial Empowerment for Entrepreneurs: Budgeting and Investment Tips

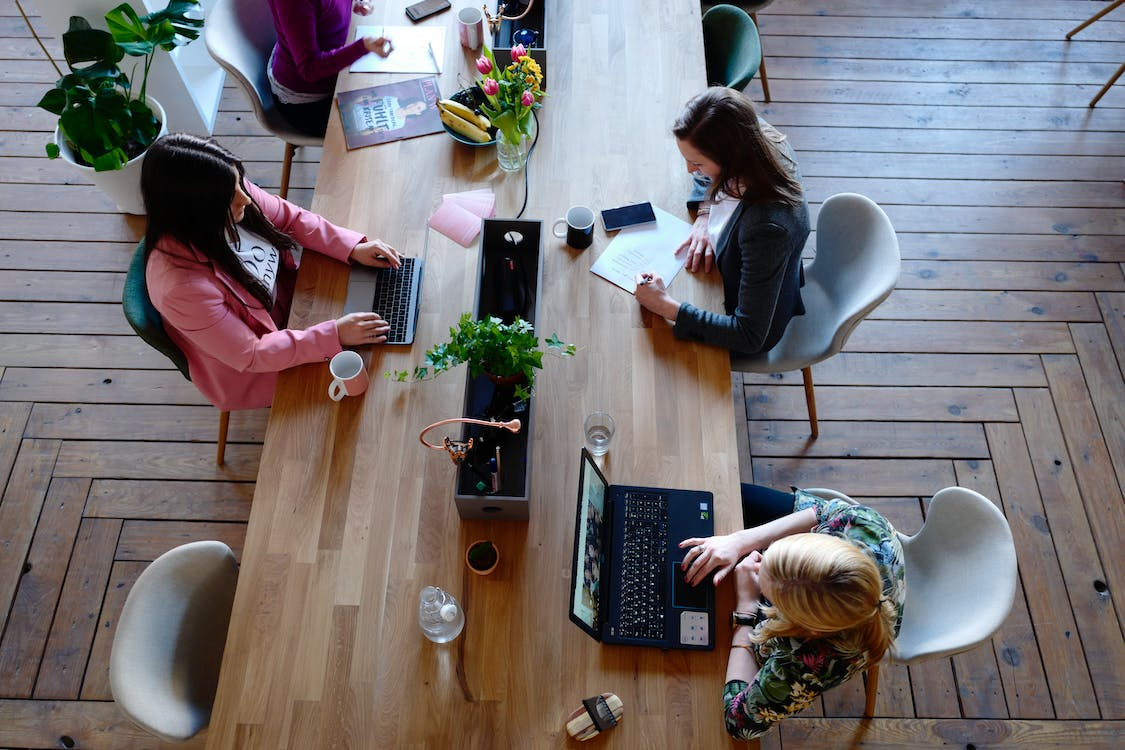
Three professionals using laptops in the office

Entrepreneurship is an exhilarating journey filled with opportunities, innovation, and growth. As an entrepreneur, you’re at the helm of your business, steering it toward success. However, amid the dynamic world of entrepreneurship, effective financial management is essential. Budgeting and investment play a crucial role in securing your financial future.

Before we dive into budgeting and investment tips, it’s important to acknowledge the vital role of a tax accountant in the Bay Area. These professionals are well-versed in the region’s intricate tax laws and can provide valuable insights to help you make informed financial decisions.

Budgeting for Financial Clarity

Budgeting isn’t about restriction; it’s about clarity. It’s the tool that lets you know where your money is going and how it aligns with your goals. Here are some tips to make budgeting work for your entrepreneurial journey:

1. Define Your Financial Goals

Start by setting clear financial goals for your business. Whether it’s expanding your product line, increasing revenue, or reducing costs, having a target in mind will guide your budget.

2. Track All Expenses

Maintain a detailed record of all your business expenses. Accurate tracking ensures you’re aware of where your money is being spent.

3. Categorize Your Spending

Categorize your expenses to understand which areas are consuming the most resources. This insight can help you identify areas for potential cost reduction or optimization.

4. Monitor Cash Flow

Cash flow is the lifeblood of your business. It’s important to track your cash flow to ensure you have enough liquidity to cover expenses, invest in growth, and weather unexpected challenges.

Investment Strategies for Growth

Budgeting sets the stage, but investment strategies are the actors that drive growth. Here are some investment tips for entrepreneurs:

1. Diversify Your Investments

Diversification is a classic strategy to reduce risk. Consider investing in different asset classes to minimize exposure to a single market’s fluctuations.

2. Explore Tax-Efficient Investments

Certain investments come with tax benefits. For example, retirement accounts like Solo 401(k)s or Simplified Employee Pension IRAs (SEP-IRAs) offer tax deferral advantages while securing your financial future.

3. Consider Long-Term Goals

Investing is a long-term game. Don’t let short-term market fluctuations sway your decisions. Focus on your long-term financial goals and stay committed to your investment strategy.

4. Seek Professional Guidance

Navigating the investment landscape can be complex. Consider hiring a financial advisor or an Indian CPA  for payroll services in Bay Area to make informed investment decisions that align with your business objectives.
A quote box atop Dollar bills

Financial empowerment is within your reach. Effective budgeting and investment strategies can transform your business’s financial health. As you embrace these practices, remember that you’re not alone in this journey.

At Nidhi Jain CPA, we understand the unique financial needs of entrepreneurs. Our team of experts, including personal accountant  in Dublin and Indian CPAs, is dedicated to your financial success.

Let’s work together to empower your financial future. Reach out to us today and discover how our financial expertise can elevate your entrepreneurial journey.
 

Related Blogs

This photo shows some tax documents on a table.

Choosing a business structure is an important decision for entrepreneurs because the entity selected can influence taxation, reporting, ownership, and ongoing compliance responsibilities. An LLC, S corporation, and C corporation each have different characteristics, and the right choice depends on the business’s circumstances rather than simply choosing the structure with the lowest potential tax burden.

This blog explains key tax and operational considerations business owners should review when evaluating an entity structure, including income, business goals, growth plans, and compliance responsibilities.

Understanding the LLC Structure

A limited liability company, or LLC, is a flexible business structure commonly used by small and growing businesses. For federal tax purposes, an LLC may receive different tax treatment depending on factors such as the number of owners and elections made by the business.

Flexibility

LLCs generally offer flexibility in management and ownership arrangements, which can make them attractive to entrepreneurs with different business models.

Tax Treatment

An LLC may be taxed in different ways depending on its circumstances. Business owners should evaluate how the chosen tax treatment fits their income and future plans rather than assuming one approach is automatically best.

Understanding an S Corporation

An S corporation is a tax designation available to eligible businesses that meet specific requirements. S corporation taxation generally allows business income to pass through to shareholders rather than being taxed at the corporate level in the same manner as a C corporation.

Ownership Requirements

S corporations have eligibility and ownership restrictions that business owners need to understand before selecting this structure.

This photo shows a calculator on top of some documents.

Compensation Considerations

Owners who work for an S corporation may need to consider payroll and reasonable compensation requirements. These responsibilities should be evaluated carefully because they can affect compliance and administrative workload.

Understanding a C Corporation

A C corporation is a separate tax entity that can be appropriate for certain businesses, particularly those with specific growth, investment, or ownership objectives.

Corporate Taxation

C corporations generally pay corporate income tax, and distributions to shareholders can create additional tax considerations. The overall tax impact should therefore be reviewed based on the company’s expected income and plans.

Growth and Investment

Businesses planning significant expansion or seeking certain types of outside investment may consider a C corporation as part of their long-term strategy.

Get Professional Guidance Before Choosing

Nidhi Jain CPA provides tax and accounting services and business tax services to help business owners evaluate their tax considerations and plan around their financial goals. Professional guidance can also support business owners with bookkeeping, tax planning, business tax filing, and other accounting needs as their companies develop.

Contact us to discuss your business structure, tax considerations, and long-term goals so the available options can be evaluated based on your specific circumstances.

This photo shows some tax documents on a table.

Unpaid taxes can become increasingly difficult to manage when they are left unresolved. Interest, penalties, collection notices, and other consequences may add pressure to an already challenging financial situation. Taking action early can help taxpayers  understand what they owe and determine which options may be available based on their circumstances.

In this blog, we will discuss practical steps for addressing back taxes, why ignoring IRS obligations can create additional problems, and when professional tax resolution assistance may be appropriate.

Start by Understanding What You Owe

The first step toward resolving tax debt is determining the amount owed and understanding which tax years are affected. Taxpayers should review IRS notices, previous tax returns, account information, and available payment records. Working with a tax consultant in San Jose can also help taxpayers better understand their outstanding obligations and available options.

If past tax returns were never filed, those returns may need to be addressed before the complete tax situation can be evaluated. Gathering accurate financial information can help establish a clearer picture of the outstanding liability and support more informed tax planning services.

Do Not Ignore IRS Notices

Ignoring IRS correspondence generally does not make an unpaid balance disappear. Notices may explain the amount due, applicable deadlines, and potential collection actions. Responding promptly can give taxpayers more time to understand their circumstances and consider an appropriate response.

Taxpayers who are uncertain about what a notice means may benefit from consulting a professional who provides tax resolution services before taking action.

This photo shows some tax documents on a table.

Review Potential Resolution Options

The appropriate approach to unpaid taxes depends on factors such as the amount owed, income, assets, expenses, filing history, and ability to pay. Depending on the circumstances, taxpayers may be able to explore payment arrangements or other IRS resolution options.

Evaluate Your Ability to Pay

Understanding current income and necessary living expenses can help establish what payment amount may be manageable.

Address Missing Tax Returns

Unfiled returns can complicate an IRS account. Making sure required returns are properly prepared and filed may be an important part of resolving the overall situation.

Consider Professional Tax Resolution Assistance

Taxpayers facing complicated liabilities, multiple years of unpaid taxes, or ongoing IRS collection activity may want professional assistance in reviewing their options.

Why Professional Guidance Can Help

Nidhi Jain CPA can help individuals understand their tax obligations and work toward addressing unresolved tax matters. Support can include reviewing tax records, helping taxpayers understand their outstanding liabilities, discussing available tax resolution approaches, and assisting with the preparation needed to move forward.

Rather than allowing unpaid taxes to remain unresolved, taxpayers can contact us to discuss their circumstances and determine what professional assistance may be appropriate.

Year-end is an important time for business owners to review their financial position and prepare for upcoming tax obligations. Waiting until tax filing season to examine income, expenses, and business decisions can leave limited time to make changes that may affect the next tax return. Proactive planning can give business owners a clearer understanding of their financial position and help them prepare for the year ahead.

This blog covers several year-end considerations, including reviewing expenses, organizing financial records, evaluating business structure, and preparing for future tax obligations.

Reviewing Business Income and Expenses

One of the first steps in tax planning in the Bay Area is reviewing the business’s income and expenses before the year closes. Comparing current financial results with previous periods can help identify significant changes in revenue, operating costs, and profitability.

Business owners can review whether financial records accurately reflect transactions completed during the year. Missing receipts, incorrectly categorized expenses, or unreconciled accounts can make tax preparation more difficult.

Working with professional bookkeeping and accounting support can help businesses maintain organized records throughout the year and make year-end reviews more efficient.

Evaluating the Business Structure

A business structure can influence how income is reported and how taxes are handled. Business owners who have experienced substantial growth, changes in ownership, or changes in their operations may want to review whether their current structure continues to suit their circumstances.

tax strategy

Factors to Review

Before making structural changes, business owners can consider:

Business Growth

Changes in revenue, profitability, or the number of owners may affect whether the current structure remains appropriate.

Tax Considerations

Different structures can have different tax treatment and reporting requirements. Reviewing these considerations before year-end can support more informed planning.

Future Business Goals

Expansion, investment, hiring, or changes in ownership may influence future tax and accounting needs.

Prepare for Future Tax Obligations

Year-end planning should not focus solely on the immediate tax return. Business owners can also consider expected income, upcoming expenses, expansion plans, and other financial changes that could affect future obligations.

A proactive approach to tax planning services may help identify potential issues earlier and create a clearer financial strategy for the coming year. It can also provide an opportunity to discuss longer-term goals rather than making decisions only around filing deadlines.

Get Professional Guidance Before the Year Ends

Nidhi Jain CPA provides business tax services for businesses seeking organized financial and tax support.

Business owners who want to review their year-end position can contact us to discuss their tax planning needs and prepare for the year ahead.