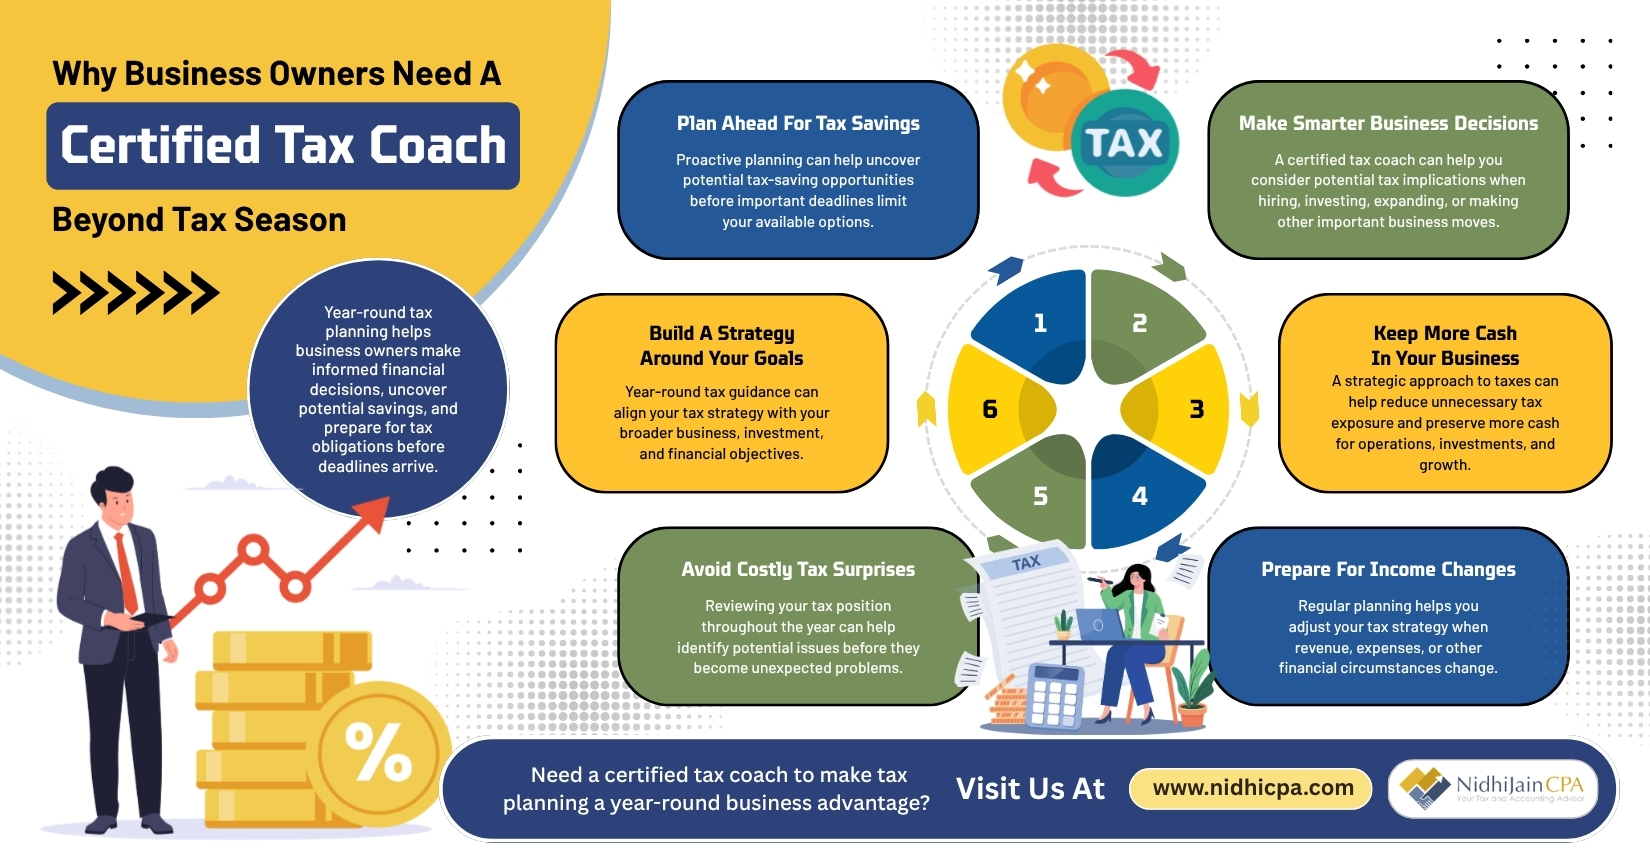

As the third quarter begins, many businesses are still managing operations on a short-term basis, without preparing for the financial year-end. That’s a mistake that could lead to missed deductions, inaccurate financial reports, and a higher tax burden. Working with a tax planning consultant early in Q3 allows businesses to stay ahead, rather than rush through major financial moves in December. Below are some important adjustments businesses should start making now to improve year-end outcomes and maintain control over tax obligations.
Review Estimated Tax Payments and Withholding
Tax underpayment penalties are entirely avoidable when a business regularly adjusts estimated payments. Many business owners assume that once estimated payments are set at the start of the year, they can leave them alone. But income, deductions, and expenses often shift throughout the year. A tax planning consultant can compare current income trends with original projections and recommend changes. If your business has grown, it might make sense to increase payments to avoid underpayment issues. If it’s slowed down, you might be overpaying. Either way, an adjustment now keeps your cash flow on track and protects you from a surprise tax bill.
Schedule Quarterly Financial Reviews
Leaving financial reviews for year-end causes errors to pile up. By conducting quarterly financial reviews, businesses catch problems early and make sure their records match reality. These reviews go beyond checking the balance sheet—they should include a full review of profit margins, expenses, accounts receivable and payable, and tax liability projections. This helps with more accurate budgeting and ensures all deductions are being properly recorded. A tax planning consultant can also use these reviews to spot areas for tax-saving strategies while there’s still time to act.
Revisit Bookkeeping Practice
Sloppy records create serious problems at tax time. Now is a good time to assess whether your bookkeeping practices are structured, consistent, and audit-ready. Ask whether income and expenses are categorized properly, whether receipts are available, and whether all bank accounts are reconciled. If your current system isn’t keeping up with your business’s growth, it may be time to consider professional bookkeeping support. Clean records help tax planning consultants work faster and more accurately.
Assess Equipment or Asset Purchases Before Year-End
Many businesses consider end-of-year equipment or vehicle purchases to take advantage of Section 179 deductions. But waiting until December doesn’t leave time for price comparisons, delivery delays, or funding approvals. Planning purchases in Q3 gives you more flexibility, and if the purchase qualifies, the depreciation benefit can reduce taxable income for the current year.
Plan Year-End Bonuses and Owner Distributions
Waiting until year-end to decide on bonuses or distributions might lead to poor timing or missed opportunities. If you want bonuses to count as a deduction for the current year, they must be paid before December 31. Reviewing year-to-date profits now allows you to make informed decisions on both employee and owner compensation. A tax planning consultant can offer insight into what’s reasonable and beneficial based on your business structure.
Where to Learn More
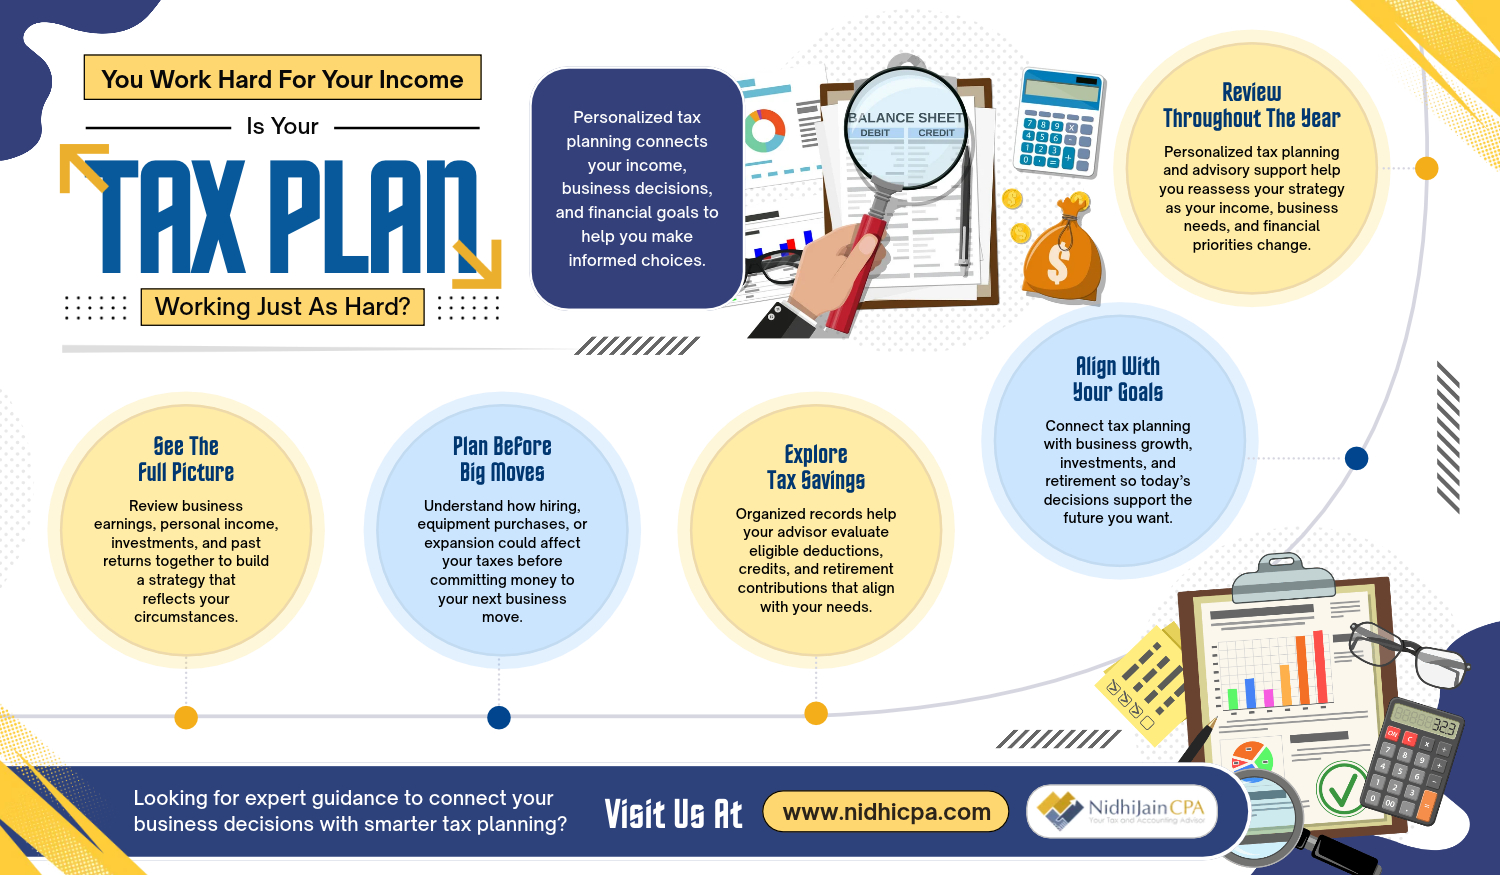
Making these adjustments now gives your business the time to address problems, apply tax-saving strategies, and improve financial clarity. It also makes Q4 easier and more predictable. If you’re looking for consistent support with bookkeeping practices, scheduling quarterly financial reviews, or understanding how a tax planning consultant can help your business in the long run, visit the blog at Nidhi Jain CPA for more insights and tax planning tips.