End-of-Quarter Bookkeeping Checklist for Bay Area Small Businesses

Running a small business comes with constant financial movement, and staying organized is what keeps everything on track. A strong end-of-quarter bookkeeping routine helps you understand where your money is going, what is working, and what needs attention before small issues turn into bigger problems.

For many business owners, especially those handling complex business taxes and bookkeeping, the end of each quarter is the perfect time to pause, review, and reset financial systems for better clarity and control.

Review and Organize Financial Records

Start by gathering all your financial documents for the quarter. This includes invoices, receipts, bank statements, and expense records. Make sure everything is properly categorized and stored. When your records are organized, it becomes much easier to track spending patterns and identify missing information. Clean records also save time when filing taxes or making financial decisions.

Reconcile Bank and Credit Card Accounts

Account reconciliation is one of the most important steps in your checklist. Compare your internal records with bank and credit card statements to ensure every transaction matches. If you notice discrepancies, investigate them right away. This process not only keeps your books accurate but also helps catch errors or fraud early.

Evaluate Income and Expenses

Take a close look at your revenue streams and expenses. Identify which areas are generating the most income and where you might be overspending. This is also a great time to cut unnecessary costs and reallocate funds to more profitable areas. A clear understanding of your financial position allows you to make smarter business decisions moving forward.

Check Accounts Receivable and Payable

Review outstanding invoices and follow up on any late payments. Keeping your accounts receivable in check improves cash flow and reduces financial stress. At the same time, ensure all your bills and vendor payments are up to date. Staying on top of payables helps maintain good relationships and avoids late fees.
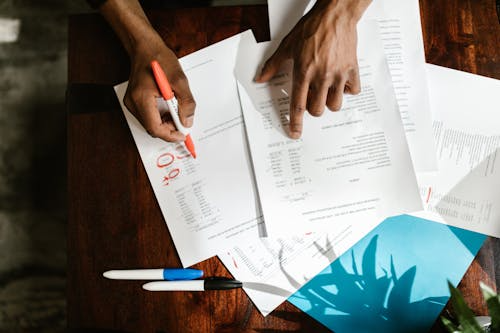
a person marking AR and AP on paperwork

Prepare for Taxes

Quarterly bookkeeping plays a key role in staying tax-ready. By reviewing your financials now, you can estimate your tax obligations and avoid surprises later. Many businesses benefit from professional tax planning services to identify deductions and reduce liabilities. In addition, staying organized supports smoother filing when it is time to handle business taxes.

Analyze Financial Reports

Generate key financial reports such as profit and loss statements and cash flow summaries. These reports give you a snapshot of your business performance over the quarter. Use them to track growth, spot trends, and set realistic goals for the next period. This step ensures your end-of-quarter bookkeeping process delivers real insights, not just numbers.

Plan for the Next Quarter

Once your books are clean and updated, use that information to plan ahead. Set financial goals, adjust budgets, and create strategies based on your findings. A proactive approach helps your business stay agile and prepared for changes in the market.

Take the Next Step Confidently

A consistent quarterly routine keeps your finances accurate, reduces stress, and improves decision-making. Whether you need help with Bay Area bookkeeping and accounting, guidance from an experienced accountant in San Jose, California, or support with tax planning, building a reliable system is key.

We at Nidhi Jain CPA are here to simplify your end-of-quarter bookkeeping and keep your business financially strong. Contact us today and get started with a more proactive bookkeeping approach.
 

Related Blogs

photo showing a person showing a document to two elderly people

Earning income from outside the United States can introduce additional considerations when preparing a U.S. tax return. U.S. citizens and resident taxpayers are generally subject to U.S. federal income tax on worldwide income, meaning certain foreign earnings and financial interests may need to be reported even when the income was earned outside the country. Understanding these responsibilities can help taxpayers avoid missed reporting requirements and unexpected tax issues. …

Laptop, notebook, and printed financial reports arranged on an office desk

Tax trouble often starts months before a return is due. A missed receipt, unreconciled bank account, or incorrect expense category can distort taxable income. The IRS generally suggests keeping tax records for three years, while employment tax records should be kept for at least four years.

That is why business bookkeeping should be handled every month, not rebuilt at year-end. A short monthly routine gives owners cleaner reports, better cash flow visibility, and stronger support for deductions.

Reconcile Every Financial Account

Compare each bank, credit card, loan, and payment processor balance with the bookkeeping system. Investigate missing deposits, duplicate charges, fees, returned payments, and transfers.

Complete this task before closing the month. Otherwise, errors can carry into future reports and make taxable profit look higher or lower than it is.

Record and Categorize Expenses

Enter every business purchase with the correct date, vendor, amount, and category. Save the receipt or invoice with the transaction.

Pay close attention to:

  • Software subscriptions
  • Insurance premiums
  • Travel and mileage
  • Advertising costs
  • Professional fees
  • Equipment purchases

Repairs, supplies, and equipment may receive different tax treatment. A certified public accountant can help set up categories that support accurate bookkeeping and accounting.

Review Receivables and Payables

Run an accounts receivable report each month. Follow up on overdue invoices and record customer payments correctly. Then review unpaid vendor bills and due dates.

Calculator and pen placed on printed business charts and financial reports

This helps owners distinguish revenue earned from cash collected. It also shows how much cash is committed to bills, loan payments, and taxes.

Check Tax Accounts

Confirm wages, employer taxes, benefits, reimbursements, and contractor payments.

Also review sales tax and estimated tax accounts. These balances should not be treated as available operating cash. Monthly checks make it easier to find missing payments before deadlines.

Run Key Financial Reports

Review the profit and loss statement, balance sheet, and cash flow report. Compare the current month with the prior month, budget, and same period last year.

Look for sharp changes in sales, margins, debt, or operating costs. Ask your CPA in Bay Area about entries that do not match business activity.

Create a Monthly Closing Checklist

Use the same steps every month and assign a completion date. Consistency reduces rushed corrections during filing season.

Keep Your Books Tax-Ready With Nidhi Jain CPA

Nidhi Jain CPA provides business bookkeeping support for owners who need organized records and clear financial reports. Our bookkeeping and accounting services include reconciliations, expense reviews, and monthly reporting. Work with our certified public accountant who can help keep your records ready for tax filing all year. Contact us now.

The United States has 36.2 million small businesses, and they employ 62.3 million people, according to the U.S. Small Business Administration.

That means millions of owners make tax, debt, and investment decisions every day. Yet many speak with a CPA only when a return is due. By then, a missed payment, weak bookkeeping process, or poorly timed purchase may be difficult to correct. Asking the right financial questions before hiring a CPA can help you find someone who supports compliance and better decisions.

What Is My Real Cash Flow Position?

Profit does not always equal cash in the bank. Ask the CPA to explain how much cash remains after loan payments, owner withdrawals, taxes, and overdue invoices.

Request a monthly cash flow forecast. It should show expected receipts, fixed bills, tax payments, and periods when cash may become tight. This helps you decide when to hire, buy equipment, or delay spending.

Are My Books Ready for Tax Filing?

Ask how often bank, credit card, loan, and payment processor accounts should be reconciled. Also ask who will review uncategorized transactions, owner payments, and unpaid invoices.

Good bookkeeping should produce a profit and loss statement and balance sheet that agree with supporting records. A certified public accountant in Bay Area should also explain which documents must be kept for deductions.

Financial professional discussing a printed report with a business owner

Am I Paying Enough Tax During the Year?

Federal income tax generally follows a pay-as-you-go system. Business owners may need withholding or estimated payments during the year.

Ask your CPA to recalculate payments when revenue, deductions, or owner income changes. Tax planning should also cover retirement contributions, asset purchases, credits, and the timing of income and expenses.

Does My Business Structure Still Fit?

The SBA states that business structure affects taxes, operations, and personal asset exposure.

Ask how your sole proprietorship, partnership, LLC, S corporation, or C corporation affects owner pay, filing costs, and state taxes. An entity change may add fees and reporting duties, so compare the full annual cost before making a decision.

What Should I Prepare for Next?

Ask for a 12-month plan covering hiring, financing, expansion, estimated taxes, retirement contributions, and major purchases. Also ask how often you will meet and which reports the CPA will provide.

Clear communication matters. Confirm which services are included, how quickly questions are answered, and who will handle your account. This helps prevent confusion when deadlines or major financial decisions arise.

Ask Better Questions With Nidhi Jain CPA

Nidhi Jain CPA helps business owners connect bookkeeping, tax planning, cash flow, and future decisions. Review the financial questions before hiring a CPA with a certified public accountant who can help build a clear financial plan based on your business needs. Contact us now.