
Profit keeps a business moving, but unmanaged tax liability can limit long-term success. Many business owners focus on increasing revenue yet overlook how taxable income affects cash flow, planning, and year-end obligations. With structured tax planning services, businesses can increase profitability while keeping tax burdens manageable.
Understanding the Relationship Between Profit and Tax Liability
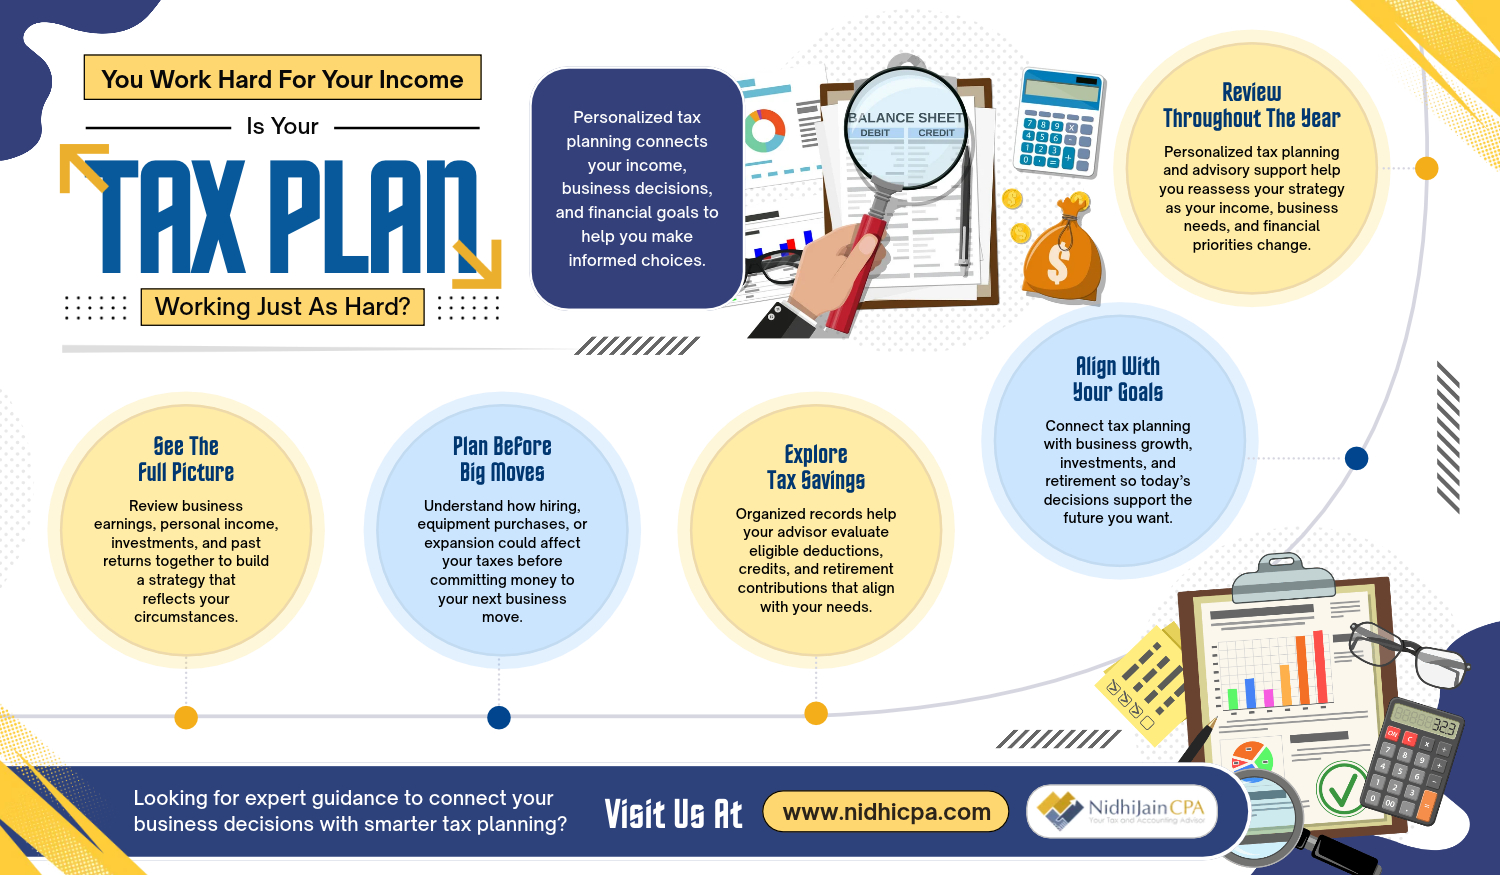
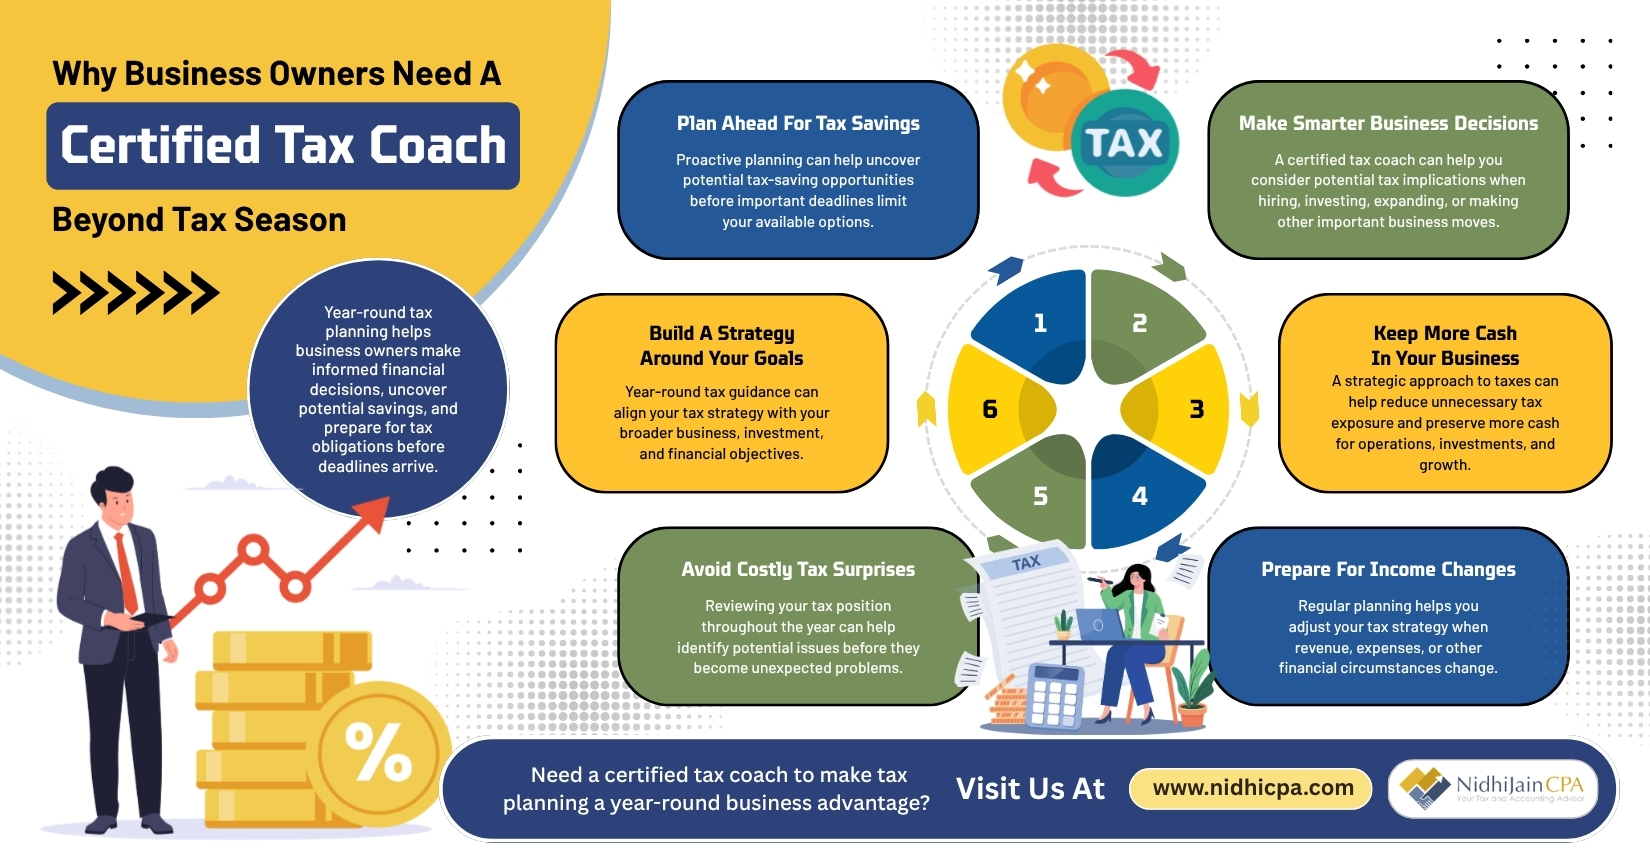
As revenues rise, taxable income increases unless expenses, credits, and deductions are managed correctly. Without a proactive strategy, businesses may face larger-than-expected tax bills that strain cash reserves. A Tax Consultant helps owners understand how business decisions, such as hiring, equipment purchases, or expanding operations, affect tax outcomes.
Business owners working with professionals such as accountants, a tax consultant, or a tax advisor gain clarity about how income flows through the tax system. This transparency helps prevent surprises and allows for smoother financial planning.
Using Tax Planning Services to Strengthen Growth
Structured tax planning services help businesses match their financial goals with tax-efficient actions. This includes timing expenses, claiming available deductions, and identifying credits that reduce taxable income. A Tax Consultant reviews records regularly and identifies strategies that align profit goals with compliance.
Businesses also benefit from proper bookkeeping practices. Clean records supported by bookkeeping allow Tax Consultants to prepare accurate projections and help owners adjust spending or reporting before liabilities accumulate.
Managing Cash Flow with Accurate Tax Estimates
One of the biggest challenges for growing businesses is balancing cash flow with tax obligations. By calculating accurate quarterly estimates, owners avoid penalties and keep funds available for operations. A professional, such as a certified public accountant, evaluates revenue patterns and prepares clear payment timelines that support growth.
This approach prevents sudden year-end bills that disrupt development plans or reduce available working capital. When supported with tax and accounting services, businesses maintain financial stability even during expansion.
Strategic Deductions That Support Long-Term Profitability
Not all deductions simply reduce taxes; many contribute directly to growth. Investments in technology, training, or equipment often qualify as deductible expenses. A Tax Consultant helps owners classify these costs correctly and identify opportunities that support operations while reducing liability.
Businesses with international income or complex reporting requirements also benefit from consulting an international tax accountant. These professionals ensure that deductions and credits align with IRS rules and prevent double taxation.
Why Sustainable Growth Requires a Holistic Tax Strategy
A business that focuses only on revenue without monitoring tax liability risks unstable cash flow, compliance issues, and reduced profitability. A holistic tax plan blends short-term decisions with long-term financial goals.
When businesses combine sound bookkeeping, accurate reporting, and consistent tax planning services, they create a structure that supports expansion while keeping tax burdens predictable.
Smarter Tax Management with Nidhi Jain CPA
Nidhi Jain CPA helps business owners balance profit and tax responsibility with strategic planning, accurate projections, and clear compliance guidance. With support from one of the best CPA professionals in the Bay Area, businesses can maintain healthy growth without facing unexpected liabilities.
Build a tax strategy that strengthens profit, not restricts it. Contact us today for year-round planning and expert support.