Payroll Taxes: What You Need To Know

a tax planner calculating taxes

The employees and employers pay payroll taxes to the federal and local governments. These taxes include all the withheld taxes from the paychecks and any taxes paid by the employer. These may include:

  • Medicare tax
  • State and federal unemployment taxes
  • State and federal income taxes
  • And finally, the social security taxes

What’s the purpose of payroll taxes?

Payroll taxes are primarily used for social insurance payments, including Medicare and Social Security benefits. Social insurance taxes amount to more than 20% of local, state, and federal government combined.

Who pays the payroll taxes?

The two major social insurance taxes include payroll taxes paid to the federal government–namely MedFICA and FICA. FICA amounts to a 12.4% tax that funds your Social Security, and MedFICA is a 2.9% tax that funds your Medicare insurance.

Half of your payroll taxes (i.e., 7.65%) are paid by your employer, while the rest is taken from your paycheck.

Unemployment benefits

Your employer has the basic responsibility to fund your unemployment insurance. They’ll have to pay for your unemployment benefits if they lay you off. However, the actual rate of the benefits will differ from one industry to another.

The part of federal payroll taxes paid by the employer toward social security insurance is used to pay for your unemployment benefits.
a tax advisor talking to her client

Social Security and payroll taxes

The chunk of your payroll taxes that goes into Social Security is divided into 2 funds: Disability Insurance Trust Fund, which pays for your disability benefits; and OASI (Old-Age and Survivors Insurance) Trust Fund, which pays for survivor and retirement benefits. Thus, after you’re retired or unemployed because of a disability, you’ll be paid out the benefits from these 2 trust funds.

Medicare and payroll taxes

Similar to the social security funds, the Medicare taxes also go into 2 funds: the Supplementary Medical Insurance Trust Fund and the Hospital Insurance Trust Fund. These funds essentially pay toward your health and medical benefits.

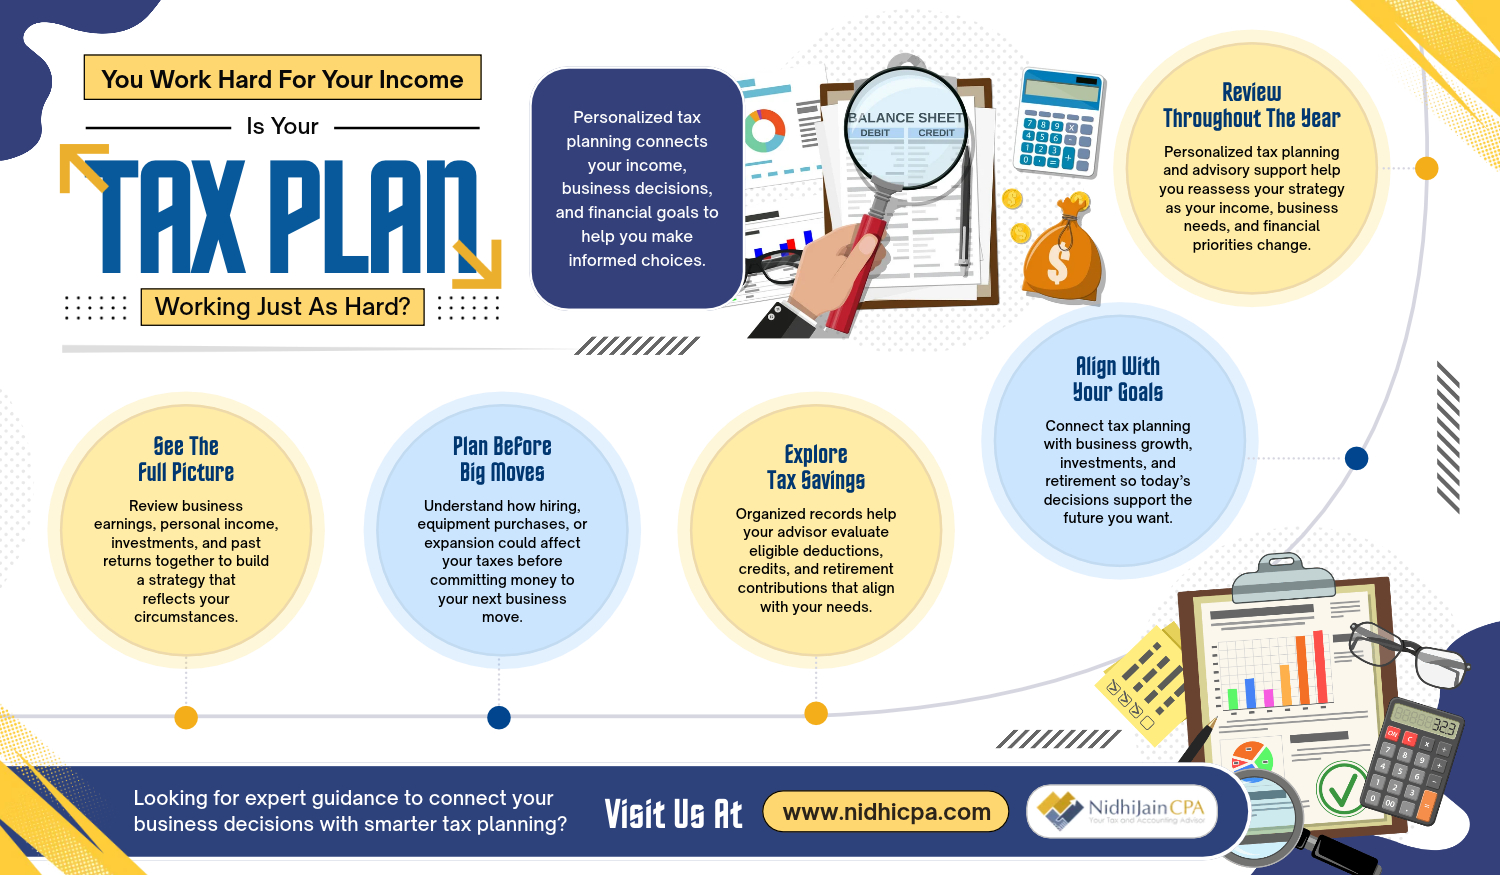
Hire tax experts at Nidhi Jain CPA

If you’re looking for tax consultants to manage your firm’s payroll taxes, we can help you. At Nidhi Jain CPA, our certified public accountants have years of experience in providing tax filing and planning services to businesses.

We also offer personal tax filing services, back tax solutions, international tax advice, and more.

Contact us today to learn more about our financial services and business tax filing in Bay Area.
Related Blogs

This photo shows some tax documents.

Receiving an IRS notice showing a tax balance can be stressful, particularly when paying the full amount is not financially realistic. Ignoring the balance, however, does not make the liability disappear. Interest and applicable penalties can continue to accrue until the amount is paid.

This guide explains what taxpayers should organize before requesting an arrangement, what payment options may be available, and how IRS payment plan help can make the process easier to navigate.

Start by Understanding What You Owe

Before requesting a payment arrangement, review your IRS notices and determine the tax year, outstanding balance, penalties, and interest involved. Your IRS Online Account can provide information about your current balance and payment history.

If you have unfiled returns, address those obligations as well. Generally, taxpayers must be current with required filings before certain payment plans can be considered.

Prepare the Information the IRS May Need

Having your financial information organized before applying can make the process more manageable.

Gather Your Tax Records

Keep copies of relevant tax returns, IRS notices, previous payment records, and correspondence together. This gives you a clearer picture of the liability you are trying to resolve.

This photo shows some tax documents.

Review Your Income

Collect recent information showing wages, self-employment income, investment income, or other sources of money you receive. Accurate income information can be important when determining what payment arrangement may be appropriate.

Document Your Regular Expenses

Review housing, utilities, transportation, insurance, food, medical expenses, debt payments, and other recurring costs. Some situations may require additional financial information or collection forms.

Do Not Wait Until Collection Problems Escalate

Addressing an unpaid balance promptly gives you more opportunity to understand available options. If you cannot pay everything immediately, paying what you can and exploring an arrangement may be preferable to simply ignoring the liability.

Professional tax resolution services can also help taxpayers review their circumstances and understand potential approaches for addressing outstanding liabilities.

Get Help Addressing an Outstanding Tax Balance

Tax debt can involve more than simply choosing a monthly payment amount. Nidhi Jain CPA provides back tax solution support, tax planning, and accounting guidance to help taxpayers understand their obligations and work toward addressing outstanding balances.

If you need a tax advisor in the Bay Area for an unresolved tax matter, contact Nidhi Jain CPA to discuss your situation.