
Digital payments are now a normal part of doing business. From Venmo and PayPal to crypto platforms and app-based transfers, money moves faster than ever — and the IRS has updated how it tracks and verifies these transactions. Beginning with new federal reporting rules rolling into the 2026 filing season, digital transactions are more visible to regulators. We regularly help clients understand what this means in practical terms and how proper documentation prevents tax surprises.
Why Digital Payments Are Getting More Attention
The IRS has increased its focus on digital transaction trails because underreporting often happens when payments move through apps instead of traditional payroll or invoicing systems. Payment platforms and digital asset brokers now have expanded reporting obligations. This does not mean every Venmo transfer is taxed — but it does mean more transactions are being matched against tax returns. Business owners working with a CPA should assume that platform-reported totals will be compared to filed income.
What Form 1099-DA Means in Simple Terms
Form 1099-DA is a new federal information return created for digital asset transactions, especially cryptocurrency and certain broker-facilitated digital transfers. Starting with phased implementation, brokers and platforms must report gross proceeds and transaction details to both taxpayers and the IRS. This is similar in concept to stock reporting, but applied to digital assets. Anyone trading or accepting digital assets for business purposes should review reporting carefully with a tax advisor before filing.
Venmo, PayPal, and App Payments for Business
Separate from crypto reporting, payment apps are also subject to third-party network reporting rules (such as 1099-K thresholds). If you receive business payments through apps, those totals may be reported even if you think of them as “casual transfers.” The IRS systems do not rely on labels like “friends and family” if patterns look business-related. That is why strong classification and reconciliation matter. Many small companies now depend on bookkeeping to separate personal transfers from business revenue correctly.
How Clean Records Reduce Digital Audit Risk
The best protection is not avoidance — it is documentation. Keep invoices, screenshots, platform statements, wallet histories, and deposit logs. Match every business payment to a purpose and category. If you accept digital payments, record them in your books the same way you would record a check or card payment. Accurate monthly reconciliation supports deductions and income reporting. A qualified personal tax accountant can align your records with what platforms report, so mismatches are resolved before filing.
Planning Ahead for Loans and Mortgages
Digital income that is properly reported and documented can strengthen — not hurt — mortgage and financing applications. Lenders increasingly review tax transcripts and revenue consistency. When digital receipts are cleanly recorded, they support income verification. Business owners seeking growth financing benefit from working with a tax planning consultant who connects bookkeeping, tax reporting, and lending readiness into one strategy.
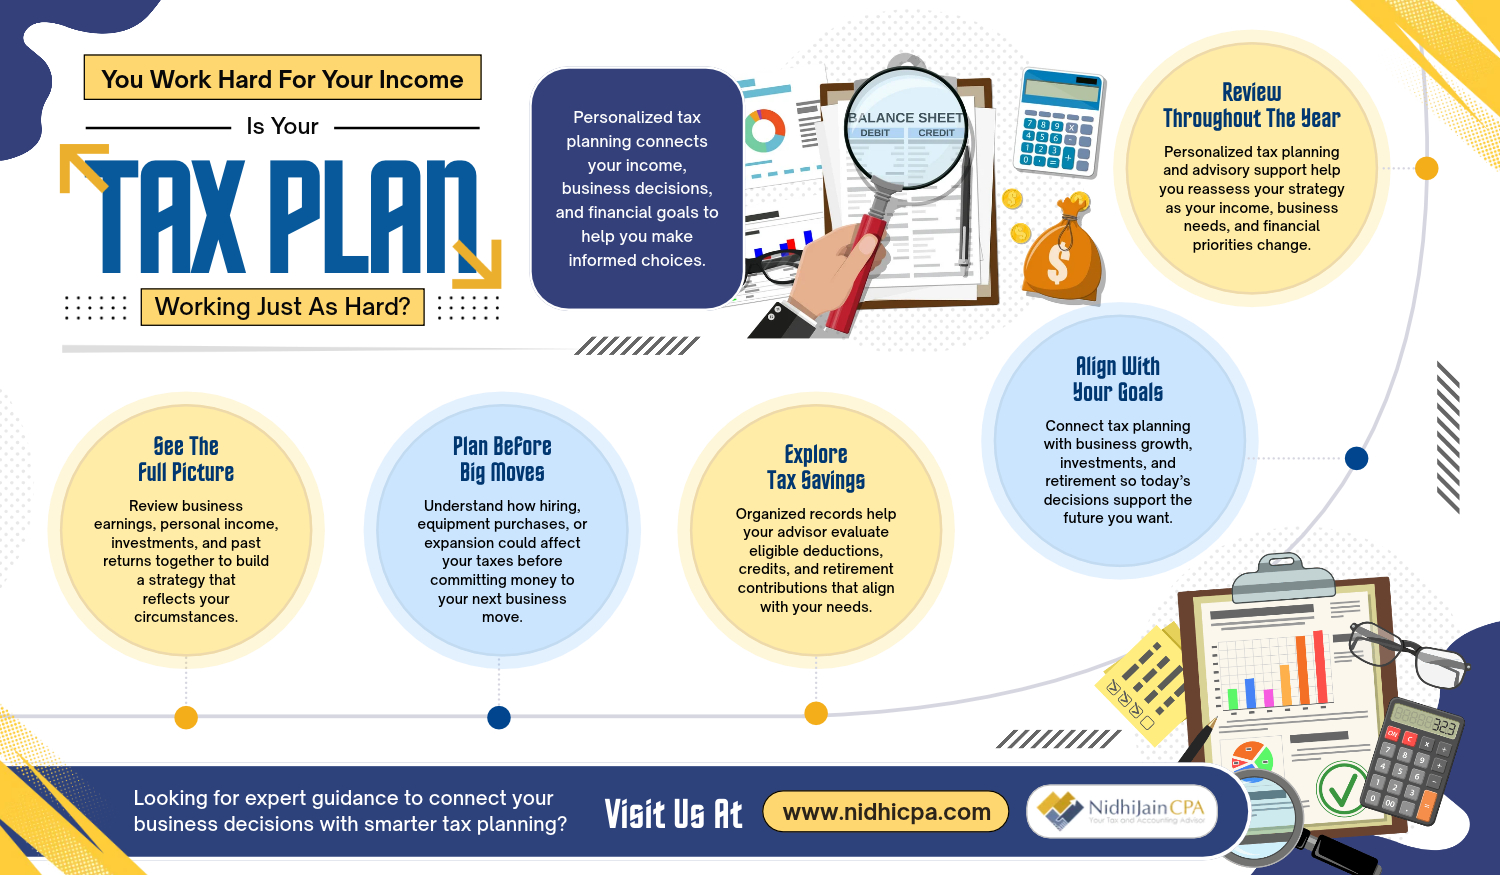
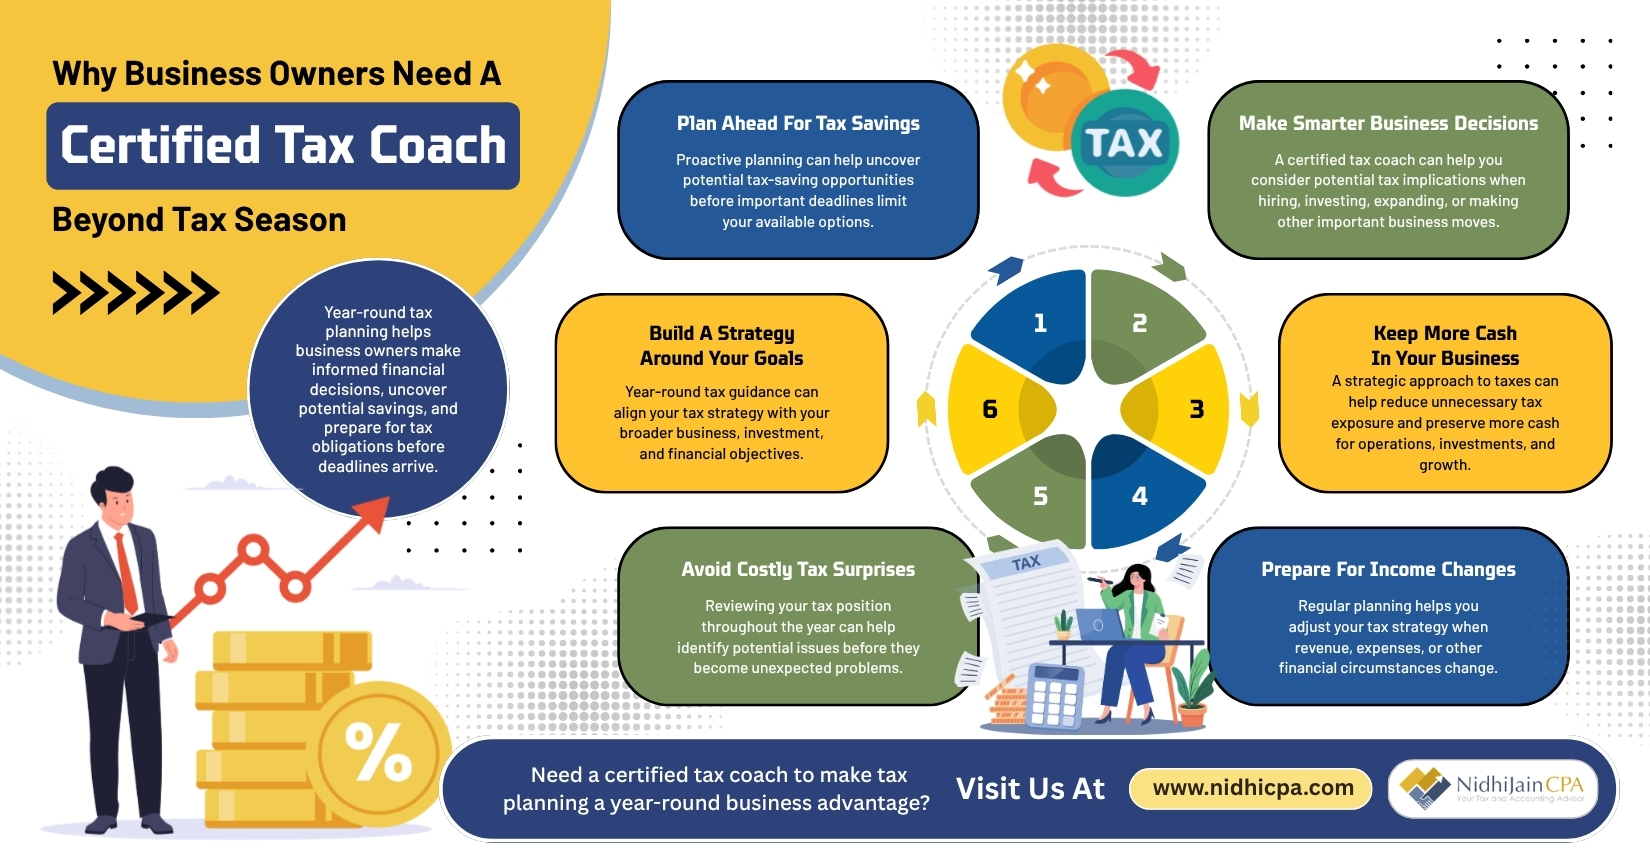
We operate with a planning-first approach at Nidhi Jain CPA, focusing on record clarity, proactive compliance, and business-centered tax decisions so digital reporting works in your favor — not against you.
Turn Digital Reporting Into a Tax Advantage
Do you feel your taxes stay high no matter how hard you plan? Many owners and professionals in San Jose face that frustration. At Nidhi Jain CPA, we design tax planning and business tax services that help reduce liability while keeping records audit-ready. If you are searching for a certified public accountant or trusted accountants in San Jose, California, we provide practical guidance, strong Bay Area bookkeeping and accounting, and accurate individual tax filing support. Explore our full tax and accounting services to see how structured planning lowers exposure. We also handle tax resolution services and back tax solutions for complex cases. Ready to move forward? Call now or visit our website to get started.